
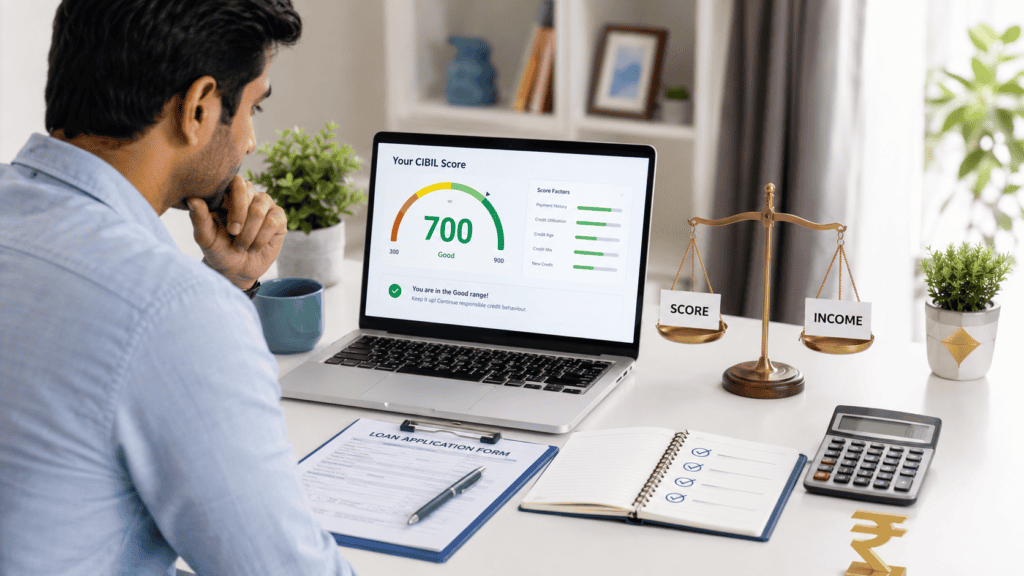
You’ve checked your credit report and seen a CIBIL score of 700. Now comes the real question: is that enough to get your personal loan or credit card approved, or should you wait? A 700 CIBIL score sits in a decent zone, but it isn’t a golden ticket. Lenders read it alongside your income, your existing EMIs, your repayment history, and how many loans or cards you’ve applied for recently.
This guide walks through what a CIBIL score 700 actually means for personal loans, credit cards, home loans, and secured loans — and, just as importantly, why a decent score can still end in rejection. You’ll get a practical apply-now-or-wait framework instead of a generic “700 is good” answer.
Every lender sets its own eligibility policy, and that policy can change. Nothing here should be read as a guarantee of approval, a fixed interest rate, or a promised credit limit.
Quick Answer: Is CIBIL Score 700 Good Enough for Approval?
CIBIL score 700 is usually a decent credit score for loan or credit card applications, but it does not guarantee approval. Indian lenders may also check income, existing EMI burden, repayment history, hard inquiries, employer profile, and documents. If your FOIR is high or recent defaults exist, approval can still be difficult.

Key Takeaways
- A 700 CIBIL score is generally viewed as decent — noticeably better than a sub-650 profile, but not automatically in the “excellent” bracket every lender prefers.
- Approval still depends heavily on your income and how much of it is already committed to existing EMIs — your debt-to-income ratio matters as much as the score itself.
- Personal loan and credit card outcomes can differ at the same score — a card issuer may look at spending behaviour differently from how an unsecured loan lender assesses risk.
- Secured options like a gold loan can be easier to get sanctioned than an unsecured personal loan, because collateral reduces the lender’s risk.
- Recent defaults, high credit utilisation, or several hard inquiries in a short window can outweigh a 700 score’s benefit.
- Improving weak spots — like overdue payments or high card usage — before applying is usually safer than applying to many lenders at once.
Key Facts at a Glance
| Aspect | What It Usually Means | What You Should Do |
|---|---|---|
| Score status | Generally treated as decent to moderately good by most lenders | Don’t assume it clears every lender’s internal cutoff |
| Best-fit approach | Selective, well-matched applications rather than applying everywhere | Check eligibility criteria before you apply |
| Main risk factors | High FOIR, recent DPD, defaults, high card utilisation, multiple hard inquiries | Review your report for these before applying |
| Improvement direction | Moving closer to 750+ can widen your options over time | Build the habit — there’s no fixed timeline lenders promise |
What a CIBIL Score 700 Actually Means for Approval
Your CIBIL score is a three-digit number, typically ranging from 300 to 900, generated by TransUnion CIBIL using the repayment data lenders report to it. A score of 700 sits comfortably above the lower bands most lenders treat as risky, but it isn’t at the top of the range either. In plain terms: it’s not a red flag, but it’s also not a free pass.
Where exactly 700 lands on a “poor to excellent” scale, and whether a specific bank treats it as sufficient, is something each lender decides internally — some may have a higher internal cutoff for their best rates or premium cards. That’s a policy detail you should check against what counts as a good score for loans at the lender you’re considering, rather than assuming one number applies everywhere.
It also helps to separate three things that often get treated as one: your credit score, your credit report, and lender eligibility.
Score, Report, and Eligibility Are Not the Same Thing
Your score is a single number. Your credit report is the fuller history behind it — every loan, card, EMI, and repayment date recorded against your name. Lender eligibility is a separate decision the bank or NBFC makes using your score, your report, and information you provide directly, like your salary slip or ITR. A 700 score with a clean report is a stronger position than a 700 score sitting on top of a recent missed payment, even though the number is identical.
Scores can also differ slightly between bureaus. TransUnion CIBIL, Experian India, CRIF High Mark, and Equifax India each calculate scores using their own models and the data lenders happen to report to them, so your Experian score and your CIBIL score won’t always be identical.
| Factor Beyond Score | Why It Matters | What You Can Check |
|---|---|---|
| Monthly income | Determines how large an EMI you can realistically support | Latest salary slips or ITR |
| FOIR / debt-to-income ratio | Shows how much income is already committed to EMIs | Add up your current EMIs against take-home pay |
| Repayment history (DPD) | Recent missed payments signal higher risk even with a decent score | Days-past-due entries in your credit report |
| Credit utilisation | High card usage relative to your limit can worry lenders | Outstanding balance versus total credit limit |
| Documents and employer profile | Weak or mismatched documents slow or stall approval | ID proof, address proof, income proof consistency |
| Job stability | Lenders often prefer a minimum tenure with the current employer | Your current employment duration |
Real Example: Two Borrowers, Same 700 Score, Different Outcomes
Meet Amit and Rohit — both 31, both salaried, both earning around ₹50,000 a month in Pune, and both sitting at a CIBIL score of exactly 700.
Amit has one existing EMI of ₹6,000, pays every card bill in full, has no missed payments in the last two years, and hasn’t applied for new credit in the last six months. When he applies for a personal loan, his file looks stable — a decent score backed by a clean, low-obligation profile.
Rohit also has a 700 score, but he’s carrying two existing EMIs totalling ₹22,000, is regularly close to his credit card limit, and applied to four different lenders in the past two months after an earlier rejection. On paper, his score looks identical to Amit’s. In practice, a lender reviewing his file sees a much higher debt burden and several recent hard inquiries — both of which can make approval harder or push the offered terms higher.
The insight: the number 700 tells a lender almost nothing on its own. What surrounds that number — your EMI load, your recent credit behaviour, and your report’s overall pattern — usually decides the outcome.
Eligibility Checklist Before You Apply at 700
- You have a stable, verifiable income source (salary or consistent business income).
- Your existing EMIs are a manageable share of your take-home pay.
- You have no recent DPD, default, or settled/written-off account on your report.
- Your credit utilisation is on the lower side rather than close to your limit.
- You haven’t applied for several new loans or cards in the last few months.
- Your documents and personal details match consistently across your PAN, address proof, and income proof.
Checking every box here improves your readiness — it does not guarantee approval, since each lender applies its own credit card score requirement or loan policy on top of these factors.
How to Calculate Your Repayment Capacity Before Applying
Lenders often lean on a simple idea called FOIR — Fixed Obligations to Income Ratio. It’s the share of your monthly income already going toward EMIs and fixed commitments. A high FOIR can work against you even with a 700 score, because it signals limited room to absorb a new EMI.
FOIR (%) = (Existing EMIs + Proposed EMI) ÷ Monthly Income × 100
Where: Existing EMIs = your current loan/card EMI outflow | Proposed EMI = the new EMI you’re considering | Monthly Income = your take-home salary or net business income
| Item | Amount | Note |
|---|---|---|
| Monthly income | ₹50,000 | Illustrative salary |
| Existing EMI | ₹12,000 | One ongoing loan |
| Proposed new EMI | ₹8,000 | New personal loan under consideration |
| Combined FOIR | 40% | (₹12,000 + ₹8,000) ÷ ₹50,000 × 100 |
Whether 40% is comfortable or stretched depends entirely on the lender’s own internal policy — different banks and NBFCs set different FOIR comfort zones, and this can change over time. What matters for you is the direction: the lower your combined obligations relative to income, the stronger your case looks, regardless of your exact score. If your existing EMI burden is already high, adding a new EMI is the more common reason for rejection — not the score itself.
Comparison: Approval Readiness Across Products at a 700 Score
| Product | Approval Possibility | What Else Lenders Check |
|---|---|---|
| Personal loan | Possible — depends on income and FOIR | Income stability, existing EMIs, employer type |
| Credit card | Possible — card type and limit may vary | Spending pattern, existing card utilisation |
| Home loan | Depends more on other factors | Property value, LTV, legal and income documentation |
| Gold loan / secured loan | Generally easier — collateral reduces lender risk | Collateral value, repayment plan |
| BNPL / small ticket credit | Use with caution | Over-borrowing risk, reporting impact on future score |
Notice the pattern: none of these are guaranteed outcomes. Each one “may” work, “can” work, or “depends on lender policy” — because that’s genuinely how approval decisions get made in practice.
Safety Checklist: Don’t Weaken Your Own Approval Chances
Applying to many lenders at once
Each formal loan or card application usually triggers a hard inquiry.
Several inquiries in a short span can make your profile look credit-hungry, even if your score is decent, and may reduce your odds rather than improve them.
Apply selectively, to lenders whose eligibility criteria you’ve actually checked.
Ignoring existing overdue payments
An overdue EMI or card bill sitting unresolved doesn’t disappear from view.
It shows up in your report as ongoing risk and can outweigh the benefit of a 700 score entirely.
Clear it first, then consider applying.
Hiding existing EMIs or debts
Some borrowers under-report their obligations on an application form.
Lenders cross-check this against your credit report — a mismatch can stall or reject your application on trust grounds alone.
Declare your obligations accurately.
Taking a high-cost loan just because it’s approved
Approval isn’t the same as a good deal — some lenders sanction quickly at a steep cost.
A high rate or heavy fee can add up to a meaningfully larger repayment over the loan’s tenure.
Compare total cost, not just approval speed.
Letting credit utilisation run high
Using most of your available card limit each month is read as a risk signal.
Keeping your credit utilisation ratio lower, and paying it down before you apply, works in your favour.
Aim to bring outstanding balances down well ahead of any new application.
How to Decide What’s Right for You
your income is stable, existing EMIs are manageable, and your report shows no recent default — applying carefully to a well-matched lender is a reasonable next step.
you need funds urgently and have collateral available — a secured option like a gold loan may be more achievable than an unsecured product right now.
your credit utilisation is consistently high, or you’ve applied to several lenders recently — pause new applications and work on those two areas first.
you have an active overdue payment on any loan or card — resolve that before applying anywhere new, since it’s likely to weigh more than your score.
an unsecured loan gets you only a high rate or heavy processing fee — it’s worth comparing the total repayment cost against waiting a few months to improve your profile.
| Situation | Apply Now / Wait | Reason |
|---|---|---|
| Stable income, low existing EMIs, clean report | Apply carefully | Profile is well-positioned beyond the score alone |
| High card utilisation, no recent defaults | Improve first | Paying down balances strengthens the application quickly |
| Recent missed payment or default | Wait | Recent negative marks tend to weigh heavily on lender review |
| Multiple recent applications | Wait a few cycles | Reduces the appearance of credit-seeking behaviour |
Common Mistakes to Avoid
Assuming 700 guarantees approval
Treating the score as a pass/fail line rather than one input among several.
Borrowers who apply expecting automatic approval are often caught off guard by a rejection tied to income or FOIR, not the score.
Check the full eligibility picture, not just the score, before applying.
Applying repeatedly right after a rejection
Reapplying to another lender within days of a rejection, hoping for a different result.
Each attempt adds another hard inquiry impact to your report, which can make the next lender more cautious, not less.
Pause, understand why you were rejected, and address that specific gap first.
Ignoring credit report errors
Assuming your report is accurate without ever checking it.
A wrongly reported missed payment or an account that isn’t yours can drag down an otherwise decent profile.
Pull your report directly from the bureau and review every entry.
Paying only the minimum due on credit cards
Treating “minimum due” as full repayment.
Interest accrues on the remaining balance, and utilisation stays high — both work against your profile over time.
Pay the full statement amount whenever possible.
Taking an unaffordable EMI just because it’s approved
Accepting the maximum EMI a lender offers rather than what you can comfortably manage.
A stretched EMI raises your FOIR for future applications and increases default risk if income dips even briefly.
Borrow to a comfortable EMI, not the ceiling you’re offered.
When This May Not Be the Right Choice
Applying right now with a 700 score may not make sense if any of the following apply to you: you have an active overdue amount on an existing loan or card; your existing EMI burden is already high relative to your income; your income is unstable or your documents don’t line up cleanly; the loan is for non-essential spending rather than a genuine need; or the rate and charges being offered are on the higher side for your risk profile.
If any of these apply to your situation, it may be worth exploring other options before committing.
Official Rules and Where to Verify
Your CIBIL score and report are maintained by TransUnion CIBIL. Other bureaus operating in India — Experian India, CRIF High Mark, and Equifax India — calculate their own scores using their own models, so it’s worth comparing reports if you want a fuller picture.
- TransUnion CIBIL — for your official CIBIL score and credit report
- Experian India — for a cross-check credit report and score
- CRIF High Mark — an additional bureau some lenders reference
- Equifax India — another bureau used in lender assessments
Credit reporting rules, lender assessment methods, and bureau processes can change. Always verify current details from the relevant bureau, lender, or official regulatory source before acting.
Expert Tips
- Pay every EMI and credit card bill before the due date — payment history carries significant weight in how your profile is read.
- Bring down your credit card outstanding before you apply for anything new, rather than after.
- Give your profile some breathing room after a rejection instead of reapplying immediately elsewhere.
- Pull your credit report and check every entry for errors before you assume the score alone is the issue.
- Apply only where your profile genuinely fits the lender’s typical eligibility pattern, rather than applying broadly and hoping.
- Keep your income documents and personal details consistent across every application you submit.
Frequently Asked Questions
Is 700 a good CIBIL score in India?
It’s generally viewed as decent to moderately good — clearly better than a low score, though some lenders reserve their best offers for higher bands. Treat it as a solid starting point rather than a finish line.
Can I get a personal loan with a 700 CIBIL score?
It’s often possible, but approval also depends on your income, your existing EMI burden, and the specific lender’s policy. A clean report alongside the score improves your chances.
Can I get a credit card with a 700 CIBIL score?
Many issuers may consider it, though the card type, credit limit, and terms offered can vary based on your income and existing credit usage as well.
Why was my loan rejected even with a 700 CIBIL score?
Rejections at a decent score usually trace back to a high FOIR, a recent missed payment, high credit utilisation, several recent hard inquiries, or a document mismatch — not the score number itself.
Is 700 enough for a home loan?
It can support an application, but home loans weigh property value, loan-to-value ratio, income proof, and legal documentation heavily alongside your score.
Should I improve my CIBIL score before applying?
If you have recent defaults, high card utilisation, or several recent applications on your report, improving those areas first is usually the safer route rather than applying immediately.
How long does it take to move from 700 to 750?
There’s no fixed or guaranteed timeline — it depends on your ongoing repayment behaviour, utilisation, and how your report evolves. Consistent on-time payments and lower card usage over several months tend to help.
Final Verdict
A CIBIL score 700 is a decent position — better than a low score, but not a guarantee of approval on its own. Whether you should apply now largely comes down to your income stability, how much of it is already tied up in existing EMIs, and whether your report is free of recent defaults or heavy card usage. If those factors line up, a careful, well-matched application makes sense. If they don’t, spending a few months strengthening your profile is usually the safer move than applying widely and hoping. Always verify your latest credit report, lender requirements, and bureau process before making a credit-related decision.
This article is for educational purposes only and should not be treated as personalised financial, credit, or legal advice. Credit scores, credit reports, lender eligibility criteria, and bureau processes can vary and may change over time. Please verify current details with the relevant credit bureau, lender, official regulatory source, or a qualified professional before making any credit-related decision.
Neha Menon writes simple, borrower-first explainers on CIBIL scores, credit reports, bureau disputes, DPD, loan settlement impact, hard inquiries, and practical credit score recovery. She focuses on helping Indian borrowers understand lender-reported data, avoid credit mistakes, and take safer next steps without false promises.