
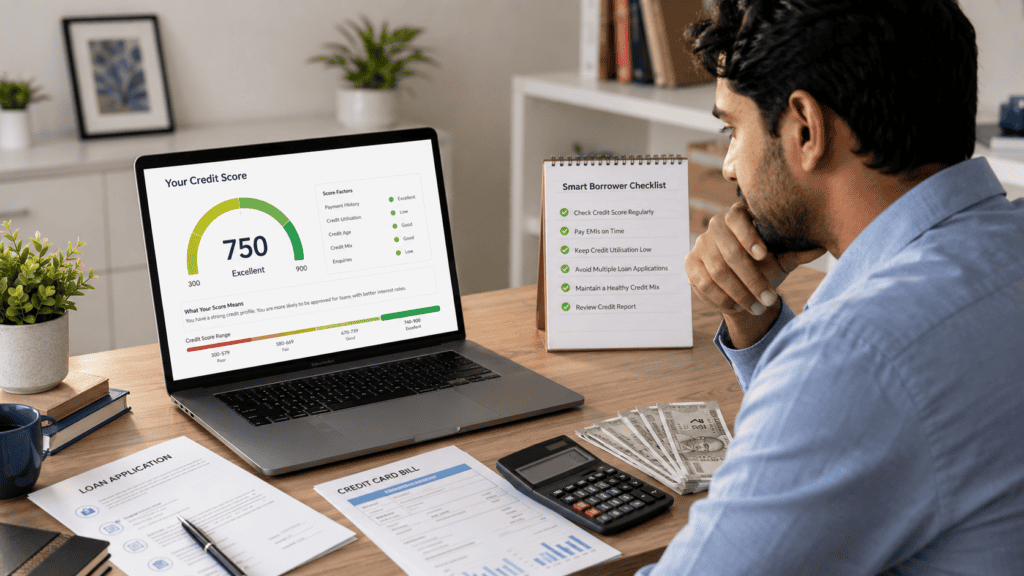
Rohit checks his CIBIL report before applying for a home loan top-up and sees a score of 750. He has heard this is a “good” number, but he does not know what it actually changes — will the bank offer him a lower rate, a bigger loan, faster approval, or all three? A 750 CIBIL score benefits borrowers in real, practical ways, but it is not a switch that guarantees anything on its own.
This guide explains exactly what a 750 score tends to open up for personal loans, home loans, car loans, and credit cards — and, just as importantly, what it does not decide by itself. Lenders still look at your income, your existing EMIs, your repayment history, and your paperwork before they say yes.
Quick Answer: CIBIL Score 750 Benefits
CIBIL score 750 benefits usually include stronger loan approval chances, more lender options, better credit card eligibility, and possible interest-rate advantages. But 750 does not guarantee approval. Lenders still check income, existing EMIs, FOIR, repayment history, documents, employer profile, and recent credit inquiries.

Key Takeaways
- A 750 CIBIL score generally places you in a strong repayment-history band, which can widen your choice of banks and NBFCs for personal loans, home loans, and credit cards.
- Any interest-rate benefit is possible, not automatic — lenders price loans using their own risk bands, your income, and the loan type, not the score alone.
- Approval still depends heavily on your FOIR (fixed obligation to income ratio), employment stability, and how clean your last 12–24 months of repayment look.
- A high credit utilisation ratio or several recent hard inquiries can weaken an otherwise strong 750 profile.
- Maintaining 750+ takes ongoing discipline — on-time EMIs, low card usage, and spaced-out applications — it is not a one-time achievement.
Key Facts at a Glance
| Item | What It Means | Borrower Action |
|---|---|---|
| 750 score band | Generally viewed by lenders as a strong, low-risk repayment profile | Use it as a planning advantage, not a guarantee |
| Approval odds | Usually improve compared with a lower score, since risk perception drops | Still keep FOIR and documents ready |
| Interest rate | May help you qualify for a better rate slab at some lenders | Compare actual offers — do not assume the lowest rate |
| Credit card access | Often widens eligibility for standard and mid-tier cards | Check income and existing card exposure too |
| What it does not guarantee | Approval, exact rate, loan amount, or card limit | Treat every offer as lender-specific |
Is 750 a Good CIBIL Score?
CIBIL scores in India run on a 300–900 scale. The closer you are to 900, the stronger your demonstrated repayment history appears to a lender. A score of 750 sits well above the midpoint and is commonly treated by many banks and NBFCs as a good-to-strong score — the kind of number that keeps you inside most lenders’ comfort zone rather than at the edge of it.
That said, “good” is not a fixed legal category. Each lender sets its own internal cut-offs and risk bands, and these can differ by product — a bank’s personal loan policy and its credit card policy may treat the same 750 score differently. You can read more about how the overall score range basics work before judging where any single number fits your situation. For a broader view of what lenders across products typically expect, see our guide on what counts as a good score for loans.
Why Lenders Prefer a Stronger Repayment History
Your CIBIL score is built from data your existing lenders report every month — timely EMIs, credit card payments, overdue amounts, and the length and mix of your credit accounts. A 750 score signals that, historically, you have paid what you owed close to on time. Lenders use this as one input into a broader risk assessment, alongside income and existing obligations, because past repayment behaviour is one of the more reliable predictors of future repayment behaviour.
Score, Report, and Lender Policy Are Not the Same Thing
It helps to separate three things borrowers often blur together. Your credit score is a number. Your credit report is the underlying record — accounts, balances, and payment history — that produces that number. And your lender’s credit policy is a separate, internal rulebook that decides how much weight the score gets compared with your income, FOIR, and documents. A strong score improves your position within that policy; it does not replace it.
Main Benefits of a 750 CIBIL Score
Across personal loans, home loans, car loans, and credit cards, borrowers with a 750 score commonly report similar practical advantages, even though outcomes vary by lender and profile.
| Product | Possible Benefit | What Lender Still Checks |
|---|---|---|
| Personal Loan | Wider lender choice, potentially quicker processing | Income, FOIR, employer type, existing EMIs |
| Home Loan | Better negotiating position on rate slab, given long tenure | Property documents, income proof, co-applicant profile |
| Car Loan | Easier approval, possibly lower margin money required | Vehicle value, down payment, income stability |
| Credit Card | Higher chance of standard or mid-tier card approval | Income slab, existing card exposure, bank relationship |
| Loan Against Property | Improved eligibility for higher loan-to-value ratio | Property valuation, ownership documents, income |
Loan Benefits for Personal Loan, Home Loan and Car Loan Borrowers
For a personal loan, being unsecured, lenders lean more heavily on your score and income stability since there is no collateral to fall back on. A 750 score can mean access to more NBFCs and banks willing to consider your application, and in some cases a shorter processing timeline.
For a home loan, the effect of even a small rate difference compounds over a long tenure — often 15 to 20 years. A borrower with a strong score may be offered a better rate slab than someone with a weaker profile, though the property, co-applicant income, and loan-to-value ratio matter just as much. See the calculation example further down to understand why this rate sensitivity matters so much for home loans specifically.
For a car loan or other secured loan, the score still matters, but the vehicle itself acts as collateral, so lenders may be more flexible on score cut-offs than they are for unsecured personal loans — while still checking your ability to service the EMI comfortably.
Credit Card Benefits With 750 CIBIL Score
A 750 score generally improves your odds of approval for regular credit cards, and in some cases opens the door to cards with higher limits or better reward structures, depending on the issuer’s internal policy. Card issuers typically also look at your income slab, your relationship with the bank, and how much of your existing credit limit across all cards you are already using.
A strong score alone will not offset a profile where you already hold several cards close to their limit, or where your income does not comfortably support another line of credit. If you want to understand the baseline expectations for card approval, see our guide on the typical card approval requirement.
Real Example: Rohit’s 750 Score, Pune
Rohit, 32, works as a marketing manager in Pune and earns around ₹85,000 a month. His CIBIL score is 750, built from three years of on-time EMI payments on a car loan and disciplined credit card repayment. He is now exploring a personal loan top-up alongside a home loan pre-approval.
He already pays ₹25,000 a month toward his existing car loan and credit card EMIs. Before evaluating any new loan, a lender will look at this existing obligation against his income — not just his score. His credit card usage stays under 30% of his total limit most months, which supports his score rather than dragging it down.
A lender reviewing Rohit’s file will likely see the 750 score as a positive signal, but the real decision on how much more he can borrow, and at what EMI, will hinge on how much room is left in his monthly income after his existing commitments — not the score number by itself.
What Lenders Check Beyond Your CIBIL Score
| Factor | Why It Matters | Example |
|---|---|---|
| Income stability | Shows consistent capacity to repay every month | Salaried vs. variable-income self-employed profile |
| FOIR / debt-to-income ratio | Measures how much of your income is already committed to EMIs | ₹80,000 income with ₹25,000 existing EMI = 31.25% FOIR before any new loan |
| Employer or business profile | Affects how a lender perceives income continuity | Established employer vs. new business with limited vintage |
| Credit history length | A longer, well-managed history builds more confidence than a short one | Five years of accounts vs. one new credit card |
| Documents and bank statements | Verifies the income and obligations the application claims | Salary slips, Form 16, bank statements, ITR for self-employed |
These checks apply on top of your score, not instead of it. For product-specific expectations, see the requirements typically expected for a personal loan requirement.
How to Calculate the Rate-Sensitivity Impact on a Home Loan
EMI = [P × r × (1+r)^n] ÷ [(1+r)^n − 1]
Where: P = loan principal | r = monthly interest rate | n = number of months
Say a lender offers two illustrative rate slabs on a ₹40,00,000 home loan over a 20-year (240-month) tenure — one that a stronger credit profile might qualify for, and one for a more average profile. These figures are illustrative only; always confirm current rates with the lender.
| Rate Slab | Monthly EMI | Total Interest Over 20 Years |
|---|---|---|
| 8.5% (illustrative) | ₹34,713 | ₹43,31,120 (approx.) |
| 9.25% (illustrative) | ₹36,633 | ₹47,91,920 (approx.) |
The difference here is roughly ₹1,920 a month — but over 20 years, that gap adds up to close to ₹4.6 lakh in extra interest. This is why even a modest rate improvement matters more on long-tenure loans like home loans than on shorter personal loans. A stronger score can help you get into a better slab, but the actual rate you’re offered still depends on the lender’s policy, your income, and the property.
Comparison: 750 CIBIL Score vs Other Score Ranges
| Score Range | Borrower Position | Key Caution |
|---|---|---|
| 650–699 | Higher Risk — approval possible but often at higher rates or with fewer lenders | Income and FOIR need to be strong to offset the score |
| 700–749 | Fair Position — reasonable approval odds at many lenders | Rate slabs may sit slightly higher than for 750+ |
| 750–779 | Strong Position — wider lender access, better negotiation room | Still lender-specific — never assumed automatic |
| 780 and above | Very Strong Position — often near the top of a lender’s risk band | Other factors like FOIR can still limit the offer |
No score range guarantees approval or rejection on its own. For a closer look at what sits just above 750, see our comparison of the card approval requirement across score bands.
If Your Score or Report Looks Wrong Before You Apply
Before submitting any application, it’s worth confirming your report is accurate — a wrong entry can quietly pull your effective score below what you expect.
Step 1 — Pull your latest report
Start by checking your report directly rather than relying on an old score estimate. You can check your report before applying for anything significant.
Step 2 — Identify the specific error
Look for an account that isn’t yours, an overdue marked against a loan you closed, or an inquiry you don’t recognise.
Step 3 — Raise a dispute
Report the error to the credit bureau or the lender that reported it, and keep a record of the dispute reference number.
Step 4 — Wait for correction if the error is material
If the mistake is significant enough to affect your score meaningfully, it is usually worth waiting for the correction before applying for a large loan.
Safety Checklist After Reaching 750
- Do not apply to several lenders at once — each hard inquiry can chip away at your score.
- Do not run your credit cards close to the limit; keep usage well below your full limit. Our credit utilisation guide explains why this matters.
- Do not take a loan simply because you are eligible for it — eligibility is not the same as need.
- Do not miss an EMI or a minimum credit card payment, even by a few days.
- Do not trust any lender or agent who promises a “guaranteed lowest rate” — actual pricing is always case-by-case.
How to Decide What’s Right for You
your score, income, FOIR, and documents are all in reasonable shape — you’re generally in a good position to compare offers and apply.
you have no recent hard inquiries and low card utilisation — lenders are more likely to view your profile favourably.
you’re comparing offers from two or three lenders rather than applying everywhere — you protect your score while still shopping around.
you’ve had a recent job change, a spike in card utilisation, or several loan enquiries in the last few months — it may be worth waiting a cycle or two before applying for something large.
your EMI affordability is untested — calculate the full EMI against your monthly budget before accepting any offer, regardless of your score.
Common Mistakes to Avoid
Assuming 750 Guarantees Approval
A common mistake is treating the score as the final word on eligibility.
Borrowers with strong scores are still turned down when their FOIR is too high or their income documentation is weak — the rejection can feel confusing precisely because the score looked fine.
Check your FOIR and gather your documents before applying, not after.
Ignoring FOIR
Many borrowers focus on the score and forget how much of their income is already committed to EMIs.
A high FOIR can cap your loan amount or trigger a rejection even with a 750 score, since lenders worry about repayment capacity under stress.
Add up your existing EMIs before deciding how much new EMI you can realistically take on.
Applying for Several Cards or Loans Together
Submitting multiple applications in a short window is a frequent error.
Each application usually triggers a hard inquiry, and several inquiries close together can pull your score down and make lenders cautious about why you need so much credit at once.
Space applications out and shortlist lenders before applying.
Closing Old Credit Accounts Without Understanding the Impact
Borrowers sometimes close old cards or loans thinking it “cleans up” their profile.
This can shorten your average credit history length and reduce your available limit, both of which can work against your score rather than for it.
Think through the effect on your credit history and utilisation before closing an old account.
Paying Only the Credit Card Minimum Due
Paying just the minimum due feels manageable but is a costly habit.
Interest accrues on the remaining balance at high card rates, and the outstanding amount also raises your utilisation ratio, both of which can quietly work against a 750-level profile over time.
Pay your full statement balance wherever possible, not just the minimum.
Treating a High Score as Permanent
Some borrowers assume 750 is now a fixed status.
A missed payment or a spike in card usage can pull the score down within a single reporting cycle.
Review your report periodically rather than checking it only when you need a loan.
When This May Not Be the Right Choice
Even with a 750 score, applying for new credit right now may not make sense if:
Your existing EMI burden already takes up a large share of your monthly income.
Your income has recently changed — a new job, a pay cut, or a shift to variable income.
You are carrying revolving credit card dues month to month rather than clearing them.
The loan purpose is discretionary and could reasonably wait, such as a large non-essential purchase.
Your emergency fund is thin, leaving little cushion if repayment gets tight.
If any of these apply to your situation, it may be worth exploring other options before committing.
Official Rules and Where to Verify
Credit scores in India are compiled by licensed credit bureaus using data reported by your lenders. It’s worth knowing where to check the details rather than relying on assumptions:
- TransUnion CIBIL — the most commonly referenced bureau for score checks and credit reports.
- Experian India, CRIF High Mark, and Equifax India — scores can vary slightly between bureaus since not every lender reports to all four.
- Your lender’s own website — for current interest rates, processing fees, and eligibility criteria, since these vary by lender and change over time.
- Your loan’s Key Fact Statement — for the exact terms of any specific offer before you sign.
You can compare this against our broader explainer on what counts as a good score for loans before applying anywhere.
Credit reporting rules, lender assessment methods, and bureau processes can change. Always verify current details from the relevant bureau, lender, or official regulatory source before acting.
Expert Tips
- Pay your full credit card statement balance before the due date, not just the minimum amount due.
- Keep your overall credit utilisation comfortably below your total limit across all cards, not just on one card.
- Keep older, well-managed accounts open where it makes sense, since they support your average credit history length.
- Space out any loan or card applications by a few months rather than applying to several lenders together.
- Review your credit report every few months, especially before a major application, so surprises don’t show up at the worst time.
- Track your FOIR alongside your score — a strong score with a high FOIR still limits what you can realistically borrow.
Frequently Asked Questions
Is 750 a good CIBIL score for loans in India?
Yes, 750 is generally viewed as a strong score by most Indian lenders, which can improve your approval odds and lender choice — though each lender applies its own internal policy.
Can I get a personal loan with a 750 CIBIL score?
A 750 score generally improves your chances, but the lender will still confirm your income, FOIR, and documents before approving the amount and rate.
Does a 750 CIBIL score guarantee low interest rates?
No. It can help you qualify for a better rate slab at some lenders, but the exact rate depends on the lender’s pricing policy, your income, and the loan type.
Is 750 enough for a home loan?
It’s often considered a strong starting point, but home loan approval also depends heavily on the property, your co-applicant’s profile, and your income documentation.
Can I get a premium credit card with 750 CIBIL?
It improves your odds for many standard and mid-tier cards. Premium cards often add income and relationship criteria on top of the score.
Why was my loan rejected despite a 750 CIBIL score?
Rejections at a good score usually trace back to a high FOIR, unstable income, incomplete documents, or a recent cluster of hard inquiries — not the score itself.
How do I maintain a 750+ CIBIL score?
Pay EMIs and card dues on time, keep utilisation low, avoid frequent applications, and check your report periodically for errors.
Is 780 better than 750 for loan approval?
A higher score can add a small further edge with some lenders, but the difference is usually smaller than the impact of your income, FOIR, and documentation.
Final Verdict
A CIBIL score 750 benefits your position as a borrower in real ways — more lender choice, stronger approval odds, and possibly a better rate slab. If your income is stable, your FOIR is reasonable, and your documents are in order, you are generally in a good position to compare offers for a personal loan, home loan, car loan, or credit card. If your EMI load is already heavy, your income has recently changed, or you have applied to several lenders in a short window, it’s worth pausing before adding new credit. Either way, calculate the EMI against your actual budget before accepting any offer — a 750 score makes options available; it does not decide affordability for you. Always verify your latest credit report, lender requirements, and bureau process before making a credit-related decision.
This article is for educational purposes only and should not be treated as personalised financial, credit, or legal advice. Credit scores, credit reports, lender eligibility criteria, and bureau processes can vary and may change over time. Please verify current details with the relevant credit bureau, lender, official regulatory source, or a qualified professional before making any credit-related decision.
Neha Menon writes simple, borrower-first explainers on CIBIL scores, credit reports, bureau disputes, DPD, loan settlement impact, hard inquiries, and practical credit score recovery. She focuses on helping Indian borrowers understand lender-reported data, avoid credit mistakes, and take safer next steps without false promises.