

You paid off your loan, but the app still shows an outstanding balance. Or a recovery agent is calling you ten times a day over a charge you never agreed to. You’ve already emailed the lender — twice — and nothing has changed. This is exactly the point where most borrowers start typing “RBI complaint” into Google, unsure if RBI can even step in, what proof they need, or whether this is even the right place to go.
RBI Ombudsman complaint process for loan issues is not the first thing you do — it’s what you do after your bank, NBFC, or lender has already had a fair chance to fix the problem and hasn’t. This guide walks you through that full path: when you’re actually eligible, what the RBI CMS portal expects from you, which documents make a complaint strong instead of ignorable, and what to do if your situation involves something more serious than a billing dispute — like harassment or fraud.
One honest note before you go further: filing a complaint is not a guarantee. RBI Ombudsman can examine service failures by regulated lenders, but it can’t promise a refund, force a settlement, or act like a court for every disagreement. Knowing that upfront will help you use the process well.
Quick Answer: RBI Ombudsman Complaint Process for Loan Issues
RBI Ombudsman complaint process for loan issues means first raising the issue with your bank, NBFC, or regulated lender, then escalating through RBI CMS if it remains unresolved after the applicable waiting period. Keep loan statements, complaint reference numbers, repayment proof, and screenshots ready before filing.
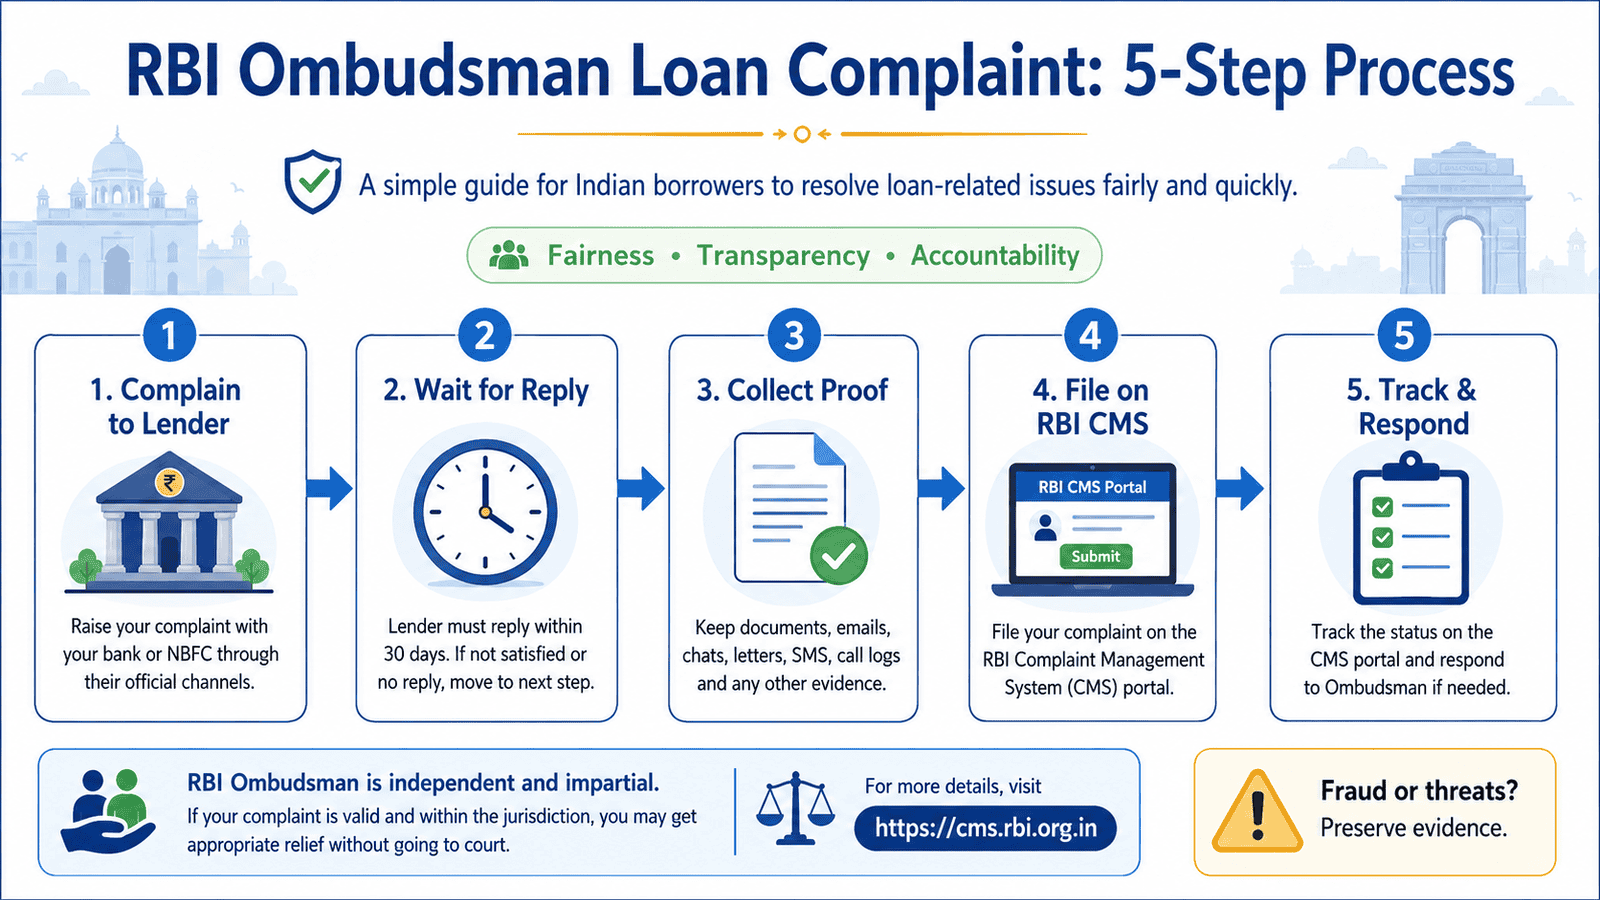
RBI Ombudsman Complaint Process: Step-by-Step
Step 1 — Identify the exact issue and who it’s against
Before writing anything, pin down two things: what exactly went wrong, and which entity is responsible. “My loan app is harassing me” is a feeling, not a complaint. “NBFC X added a ₹2,400 charge after my loan was fully closed on [date]” is a complaint. Write down the loan account number, the entity’s name, and a one-line description of the problem.
Step 2 — File with the lender’s grievance channel first
Every bank and NBFC is required to have an internal grievance redressal mechanism. Send your complaint through their official email, app, or grievance officer contact — not a phone call alone, since phone calls leave no paper trail. Note the date you filed and save any acknowledgement or ticket number you receive.
Step 3 — Wait for a response or non-resolution
Lenders are expected to respond within a set timeframe under current RBI rules. [CONFIRM — verify current figure before publishing] If the lender doesn’t respond within that window, rejects your complaint, or gives a response you find unsatisfactory, you become eligible to escalate.
Step 4 — File on RBI CMS with your proof
Once you’re eligible, you can file a complaint on RBI’s Complaint Management System portal at cms.rbi.org.in. You’ll typically need to enter your personal details, the lender’s name, a description of the issue, the date you first complained to the lender, and your supporting documents. RBI complaint against a bank or NBFC walks through this filing step in more depth if you want the fuller picture.
Step 5 — Track your complaint and respond to queries
After filing, you’ll receive a complaint reference number — save it immediately. RBI may come back to you for clarification or additional documents. Respond promptly and stick to facts. Delayed or vague responses can stall your own case.
Key Takeaways
- RBI Ombudsman is almost never the first step — your bank or NBFC’s grievance channel comes first, and you need proof you tried that route.
- A complaint backed by dates, reference numbers, and documents gets taken seriously; emotional wording without proof usually doesn’t.
- Always file through the official RBI CMS portal at cms.rbi.org.in — never through unofficial links or third-party “complaint filing” services.
- If your issue involves threats, blackmail, or misuse of your data, RBI Ombudsman alone is not enough — the cybercrime portal is the faster, more relevant route.
- RBI Ombudsman can examine service deficiency by a regulated entity, but it cannot promise you a refund, a waived charge, or a closed case.
- Keep your complaint focused on one clear issue per lender — mixing multiple unrelated grievances weakens your case.
Key Facts at a Glance
| Question | Answer | Notes |
|---|---|---|
| Who can complain | Any customer of an RBI-regulated bank, NBFC, or payment entity | Lender must be RBI-regulated |
| Where to complain | cms.rbi.org.in (RBI CMS portal) | Official portal only |
| What’s needed first | Proof you complained to the lender and didn’t get resolution | Waiting period applies — [CONFIRM] |
| Cost to file | No fee for filing an RBI Ombudsman complaint | Verify on official portal |
| What it can’t fix | Pure fraud, threats, or non-regulated entity disputes | Use cybercrime.gov.in instead |
What Is the RBI Ombudsman for Loan Issues?
The Reserve Bank Integrated Ombudsman Scheme is a free grievance redressal mechanism run by RBI for customers of regulated entities — banks, NBFCs, and certain payment system participants. Think of it as a backstop: when a lender’s own grievance process fails you, RBI Ombudsman is the body that can step in and examine whether there was a deficiency in service.
A “regulated entity” here simply means an institution that RBI directly supervises — scheduled commercial banks, RBI-registered NBFCs, and select payment companies. This matters because the Ombudsman scheme only applies to these entities. An unregistered lending app operating outside RBI’s oversight technically falls outside this route, even though the harm it causes can be very real.
It helps to separate two things people often confuse. Your lender’s grievance cell is the bank or NBFC’s own internal team — they’re the first point of contact, and by rule, you have to try them first. RBI Ombudsman is external and independent of the lender; it only gets involved once that internal route has been exhausted or has failed you. If your loan still shows as open after full repayment, loan not closed after payment covers what to do at the lender stage before this escalation even becomes necessary.
Loan problems that typically fit this route include: charges added after foreclosure or closure that weren’t disclosed upfront, a loan account that remains marked active despite full repayment, an outstanding amount that doesn’t match your own repayment records, and service-related failures like unreasonable delays in issuing a No Objection Certificate.
Real Example: Rahul’s Closed-Loan Charge Dispute
Rahul, 34, works in IT in Pune and earns around ₹55,000 a month. He took a ₹2 lakh personal loan from an NBFC and closed it on schedule after 18 months. A month later, the NBFC’s app still showed a ₹3,100 “pending charge” and sent him a payment reminder.
Rahul first emailed the NBFC’s grievance officer with his loan account number, his final repayment receipt, and a screenshot of the app showing the disputed charge. He got an auto-acknowledgement but no real resolution after the response window had passed. At that point, he gathered his loan statement, the original email with its timestamp, the receipt, and the screenshot, and filed a complaint on RBI CMS, referencing his earlier email and the date he sent it. He noted his complaint reference number the moment it arrived.
His case is still under review, and he’s aware RBI cannot guarantee the charge gets reversed — but having a clean paper trail meant his complaint had something concrete to examine. If your dispute is specifically about a number that doesn’t match what you’ve paid, wrong outstanding amount goes deeper into building that proof.
The insight that mattered most for Rahul: a complaint with dates, receipts, and a reference number gets read differently than one with frustration alone.
RBI Ombudsman Eligibility Checklist
| Requirement | Why it matters | Ready? |
|---|---|---|
| Lender is an RBI-regulated bank/NBFC | Ombudsman scheme only covers regulated entities | Check first |
| You’ve already complained to the lender | This is a precondition for escalation, not optional | Confirm with proof |
| You have a complaint reference or email trail | Shows RBI you followed the correct order | Save before filing |
| Lender’s response window has passed, or reply is unsatisfactory | Defines when you actually become eligible — [CONFIRM] | Check current rule |
| Supporting documents are ready | Statements, receipts, and screenshots strengthen your case | Gather in advance |
Documents Needed Before Filing
| Document | Example | Why needed |
|---|---|---|
| Loan account statement | Latest statement showing balance or transaction history | Establishes the factual record |
| Prior complaint proof | Email to grievance officer, app ticket, reference number | Proves lender-first escalation |
| Repayment proof | Bank transfer receipt, payment confirmation SMS | Supports closure or payment disputes |
| Key Facts Statement (KFS) or loan agreement | Original sanction document, if available | Clarifies originally agreed terms |
| NOC or closure letter | Lender-issued closure confirmation, if received | Useful for “loan not closed” disputes |
| Screenshots | App showing wrong balance, harassment messages | Visual evidence of the issue |
Loan Complaint Type vs Correct Forum
| Problem | First action | Other route |
|---|---|---|
| Wrong charge after loan closure | Lender grievance cell first | RBI CMS if unresolved |
| Loan account not closing after full payment | Lender grievance cell first | RBI CMS if unresolved |
| Recovery agent rude behaviour, but no threats | Lender grievance cell first | RBI CMS if unresolved |
| Threats, blackmail, or misuse of contacts/photos | Preserve evidence immediately | Cybercrime complaint for loan fraud |
| Lender is an unregistered app, not RBI-regulated | RBI Ombudsman may not apply | Cybercrime portal or police complaint |
| Dispute needs compensation beyond service correction | May need legal route | Consult a legal professional |
Safety Checklist If Your Issue Involves Harassment or Fraud
Safety Checklist
- Preserve call logs, recovery messages, and chat screenshots — don’t delete anything, even threatening ones.
- Never share your OTP, Aadhaar or PAN copies, or extra app permissions under pressure from a recovery call.
- Keep a written timeline of harassment incidents with dates and times.
- File complaints only through official channels — RBI CMS, your lender’s grievance email, or cybercrime.gov.in.
- If you’re facing threats or blackmail, treat it as a cybercrime matter separately from your loan dispute — see loan app harassment complaint steps for the full process.
How to Decide What’s Right for You
your issue is a billing or service dispute with an RBI-regulated lender and you’ve already complained to them — file with RBI CMS once the lender’s response window has passed.
your loan shows as open after full repayment — collect your repayment proof and closure-related documents before filing anywhere.
a recovery agent is being aggressive but not threatening — document the behaviour and check loan recovery agent rules before deciding your next step.
you’re facing blackmail, threats, or misuse of your personal data — the cybercrime route may be more urgent than an RBI complaint.
you haven’t yet complained to your lender directly — do that first; RBI CMS will expect proof of this step.
the amount you owe is genuinely overdue and undisputed — a complaint won’t erase a real debt; focus on resolving repayment terms with the lender instead.
When This May Not Be the Right Choice
When This May Not Be the Right Choice
If your lender is not an RBI-regulated bank or NBFC, the Ombudsman scheme generally won’t apply to your case — you’ll need to look at cybercrime reporting or a legal route instead.
If your dispute is fundamentally a legal disagreement — say, over contract terms requiring interpretation — RBI Ombudsman isn’t built to resolve that; a legal professional is.
If the core issue is fraud, blackmail, or cyber harassment, the cybercrime portal is the faster and more appropriate first stop, not RBI Ombudsman.
If you haven’t yet complained to the lender or don’t have any proof of doing so, your RBI complaint is likely to be sent back for that step first.
If any of these apply to your situation, it may be worth exploring other options before committing.
Official Rules and Where to Verify
Before filing, verify the current process directly from these official sources rather than relying on this article alone:
- RBI — rbi.org.in — for the Reserve Bank Integrated Ombudsman Scheme and general complaint guidance
- RBI CMS — cms.rbi.org.in — the official portal for filing and tracking eligible complaints
- National Cyber Crime Portal — cybercrime.gov.in — for fraud, blackmail, or data misuse complaints
- Your lender’s official website — for their current grievance officer contact and escalation matrix
Rules, rates, charges, and eligibility conditions can change. Always verify current details from the official source, lender, or relevant regulator before making a financial decision.
Common Mistakes to Avoid
Common Mistakes to Avoid
Filing with RBI before complaining to the lender
Many borrowers skip straight to RBI CMS out of frustration.
RBI typically requires proof that you approached the lender first — skipping this step usually means your complaint gets redirected back, costing you weeks.
Always file your grievance with the lender’s official channel first and keep that proof.
Not saving the complaint reference number
Borrowers sometimes lose track of ticket or reference numbers from their lender complaint.
Without it, you can’t prove when or how you first raised the issue, weakening your RBI complaint significantly.
Save every reference number and acknowledgement the moment you receive it.
Uploading incomplete proof
Some complaints are filed with just a description and no supporting documents.
A complaint without statements, receipts, or screenshots is far harder to evaluate and may get closed without resolution.
Attach your loan statement, repayment proof, and relevant screenshots before submitting.
Mixing fraud, harassment, and service issues into one complaint
Borrowers sometimes combine a billing dispute with harassment allegations in a single RBI complaint.
This dilutes the case and can delay handling, since service issues and cybercrime matters go through different processes entirely.
File the cybercrime complaint separately at cybercrime.gov.in if threats or fraud are involved.
Using emotional or accusatory language instead of facts
It’s natural to want to vent frustration in a complaint, but charged language doesn’t add weight to your case.
A complaint built around dates, amounts, and documented facts is taken more seriously than one built around how unfair the situation feels.
Stick to a factual, chronological account of what happened.
Assuming a complaint guarantees a refund or score correction
Some borrowers file expecting an automatic reversal of charges or a fixed credit score.
RBI Ombudsman examines service deficiency — it doesn’t promise compensation, refunds, or any specific outcome.
Treat the complaint as a fair hearing, not a guaranteed fix.
Ignoring genuinely overdue dues while filing a complaint
Occasionally a borrower files a complaint to push back on recovery calls for an amount they genuinely still owe.
This rarely works in your favour and can complicate your case if the underlying dues are valid.
Acknowledge genuine dues honestly and focus your complaint on the specific service failure.
Expert Tips
Expert Tips
- State your loan account number, exact dates, and amounts in the first two lines of your complaint — don’t bury the facts.
- Attach documents in a logical order: statement, repayment proof, prior complaint email, then screenshots.
- Build a simple timeline before you file — date of issue, date you complained, date of lender’s reply or non-reply.
- Ask for a specific, reasonable resolution in your complaint rather than a vague demand.
- Save every acknowledgement, auto-reply, and reference number — even ones that seem unimportant at the time.
- Keep your tone factual and calm; a clear account of events reads better than an emotional one.
Frequently Asked Questions
Frequently Asked Questions
Can I file an RBI Ombudsman complaint for a personal loan issue?
Yes, if the lender is an RBI-regulated bank or NBFC and you’ve already complained to them without resolution, a personal loan service issue can be eligible for RBI Ombudsman escalation.
Do I need to complain to the bank or NBFC before going to RBI?
Yes. Approaching the lender’s grievance channel first is a precondition for filing with RBI CMS — you’ll typically need to show proof of this step.
Is an RBI Ombudsman complaint free?
Filing an RBI Ombudsman complaint does not involve a fee, though you should confirm current details on the official RBI CMS portal before filing.
Can I complain against a loan app to RBI?
You can complain if the app is operated by, or tied to, an RBI-regulated bank or NBFC. If the app itself is unregistered and not regulated by RBI, the Ombudsman scheme may not apply, and a cybercrime or police complaint may be more appropriate.
What documents are needed for an RBI loan complaint?
Typically your loan account statement, proof of your earlier complaint to the lender, repayment receipts, and any relevant screenshots or correspondence.
Can RBI Ombudsman stop loan recovery calls?
RBI Ombudsman can examine whether a regulated lender’s recovery practices involved a service deficiency, but it cannot act as an immediate or guaranteed way to stop calls. For ongoing harassment, loan recovery agent rules explains the relevant conduct standards.
What if my issue is loan app fraud or blackmail?
If your situation involves threats, blackmail, or misuse of your data, this falls outside what RBI Ombudsman is built to address. Preserve your evidence and file through the National Cyber Crime Portal at cybercrime.gov.in.
What happens if RBI rejects or closes my complaint?
RBI may close a complaint if it falls outside the scheme’s scope, lacks sufficient proof, or doesn’t show prior lender escalation. You may still have other options, including approaching the lender again with more documentation or seeking legal advice for unresolved disputes.
Is there a time limit for filing an RBI Ombudsman complaint?
Yes, current rules set time limits relating to when the issue occurred and when the lender responded.
Final Verdict
Final Verdict
The RBI Ombudsman complaint process for loan issues works best for borrowers who’ve already given their lender a fair chance to fix a genuine service problem — a wrong charge, an unclosed loan, or a mismatched outstanding amount — and have the proof to back it up. If that’s your situation, build your document trail, file with the lender first, and escalate to RBI CMS only once that step is complete. If your situation involves threats or fraud, don’t wait on this process — preserve evidence and head to the cybercrime route in parallel. The safest next step, in either case, is to keep a clear, factual record of everything from day one.
Always verify the latest rules, charges, and terms from the relevant official source or provider before making a financial decision.
This article is for educational purposes only and should not be treated as personalised financial, credit, tax, or legal advice. Rules, rates, charges, eligibility criteria, and product terms can vary by provider and may change over time. Please verify current details from official sources, the relevant provider, or a qualified professional before making any financial decision.
Related Guides
Arjun writes clear borrower-safety guides on digital loan apps, RBI digital lending rules, KFS, APR, LSPs, loan app harassment, cybercrime complaints, CIBIL impact, and safer borrowing choices. He focuses on helping Indian borrowers understand risks, protect their data, compare lenders carefully, and use official complaint channels when needed.