

If a loan app has threatened you, taken money through a fake processing fee, misused your phone contacts, or sent you blackmail messages — you are not alone, and you have official options. Loan app fraud in India is a real and growing problem, and filing a cybercrime complaint for loan app fraud is the right starting point for most borrowers in this situation. The challenge is knowing exactly what proof to save, which official channel to use, and what to avoid doing in the first few hours — because panic-driven mistakes like deleting messages, paying more money out of fear, or sharing documents with unknown callers can seriously weaken your case. This guide walks you through the full complaint roadmap: evidence preservation, the National Cyber Crime Reporting Portal, the cybercrime helpline, RBI and Sachet escalation, and practical safety steps — explained without legal jargon or false promises about outcomes.
Quick Answer: How to File a Cybercrime Complaint for Loan App Fraud
A cybercrime complaint for loan app fraud can be filed through cybercrime.gov.in or the 1930 helpline if money was lost. Save screenshots, UPI references, call logs, app details, and threat messages first. Also verify whether any RBI-regulated bank or NBFC is involved before escalating separately.
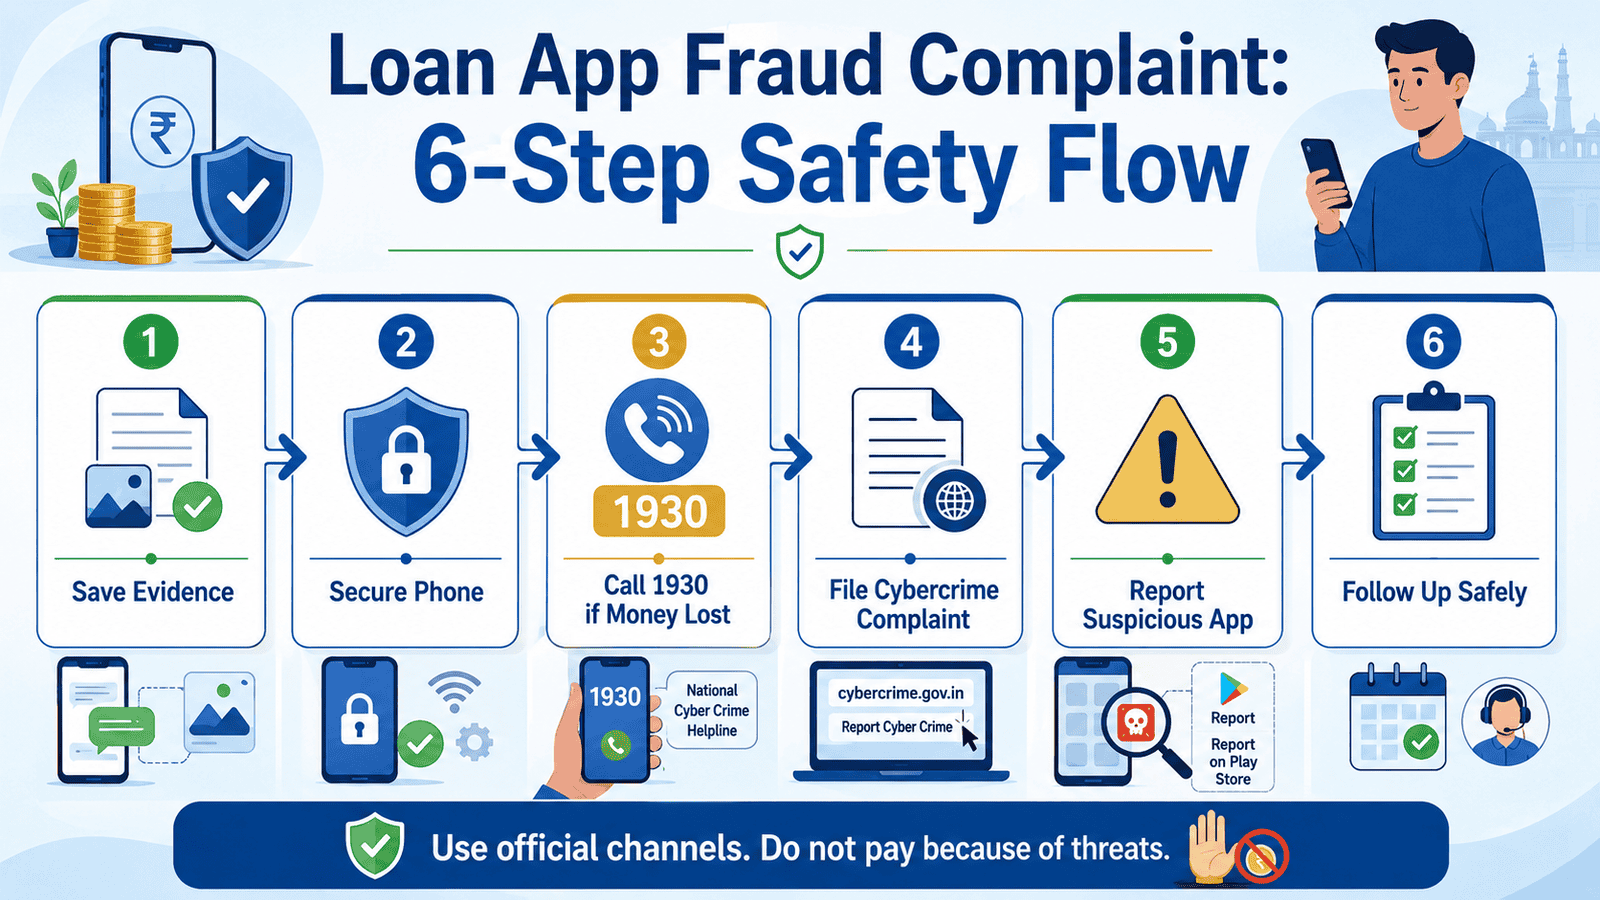
Complaint and Action Process: What to Do Right Now
Step 1 — Save Evidence Before You Delete Anything
Take screenshots of the loan offer screen, disbursal confirmation, repayment demand, and every threatening message. Export WhatsApp chats as a backup. Note every phone number, UPI ID, app name, and website shown. Do not uninstall the app yet — the app store link and version details may be needed when filing your complaint.
Step 2 — Secure Your Phone and Bank Account
Go to your phone’s app settings and revoke all permissions granted to the loan app — especially contacts, camera, gallery, and microphone. Change your net banking password and UPI PIN if you shared them or entered them in the app. Enable two-factor authentication on your bank account and email. If you suspect an active unauthorized transaction, inform your bank immediately.
Step 3 — File a Cybercrime Complaint Through the Official Portal
Visit cybercrime.gov.in and select the relevant complaint category — financial fraud, online harassment, or cyberbullying depending on your situation. Log in or register, fill in the incident details clearly, upload your screenshots and transaction proof, and save the complaint acknowledgement number. Keep a copy of everything you submitted.
Step 4 — Call the Cybercrime Helpline If Money Was Recently Lost
If money was transferred to a fraudulent app or fake account within the last few hours or days, call the national cybercrime helpline at 1930. This helpline handles financial fraud calls and may be able to initiate a quick-response process with banks. Verify current helpline hours and instructions before relying on this step, as procedures can change.
Step 5 — Use RBI, Sachet, or Lender Grievance Channels Where Relevant
If the app names a specific bank or NBFC as the lender, verify whether that entity is genuinely RBI-regulated by checking the RBI website. If regulated, you can separately raise a grievance through the lender’s official grievance redressal officer. If the entity appears suspicious or unregistered, report it through the Sachet portal at sachet.rbi.org.in. These steps are additional — they do not replace your cybercrime complaint. For detailed harassment-specific steps, see the harassment complaint steps guide.
Safety Checklist: What to Do and Avoid During Loan App Harassment
| Do This | Don’t Do This | Why It Matters |
|---|---|---|
| Save all screenshots and chat exports before doing anything else | Do not delete messages, call logs, or the app in a panic | Evidence is the foundation of every complaint |
| Revoke app permissions and change passwords after saving evidence | Do not share OTPs, Aadhaar/PAN images, or passwords with any unknown caller | Sharing documents under pressure can cause additional harm |
| Warn close contacts calmly if harassment messages have already been sent | Do not pay fresh “settlement” or “clearance” money to unknown numbers | Additional payments to fraudulent accounts rarely stop threats |
| File a complaint through official cybercrime channels | Do not post sensitive personal details or screenshots publicly on social media | Public exposure can increase harassment and complicate complaints |
| Contact police immediately if any threat involves physical safety | Do not assume every recovery call is fake without checking lender records | Genuine dues from a regulated lender should be addressed separately |
If a loan app has accessed and misused your phone contacts, read the detailed guide on contacts accessed by app for the next steps.
Key Takeaways
- Save all evidence — screenshots, UPI transaction references, chat exports, call logs, and the app store link — before deleting anything or uninstalling the app. Your complaint is only as strong as the proof you submit.
- The National Cyber Crime Reporting Portal at cybercrime.gov.in is the primary official channel for reporting online fraud, blackmail, threats, and unauthorized recovery harassment from loan apps.
- If money was recently lost to a fraudulent account, call the cybercrime helpline at 1930 as soon as possible — but verify current helpline instructions before calling, as processes can change.
- Do not pay additional money only because a loan app threatens you with contact exposure or legal action — paying extra to fraudulent numbers rarely stops harassment and may strengthen the fraud.
- Check whether any RBI-regulated bank or NBFC is genuinely connected to the app. If yes, escalate separately through that lender’s grievance redressal officer and through the RBI Complaint Management System.
- Keep your complaint acknowledgement number, submission date, and all uploaded proof safely stored. You will need these for follow-up and for any police or bank inquiry.
Key Facts at a Glance
| Issue Type | Best First Complaint Channel | Supporting Channel |
|---|---|---|
| Money transferred to fake app or processing fee scam | cybercrime.gov.in + 1930 helpline (verify current process) | Bank fraud desk |
| Threats, blackmail, or abusive recovery calls | cybercrime.gov.in (cyberbullying / harassment category) | Local cyber police station |
| Contact misuse or edited photos shared | cybercrime.gov.in + local police FIR | State cyber cell |
| Suspicious or unregistered lender scheme | sachet.rbi.org.in | cybercrime.gov.in |
| Abusive recovery by a regulated bank/NBFC | Lender grievance redressal officer | RBI Complaint Management System |
| Urgent physical threat or danger | Local police station / 112 | Cyber police station |
What Counts as Loan App Fraud?
Not every loan app complaint is the same, and the complaint route depends on what actually happened. Understanding the type of issue you are facing helps you choose the right channel and describe the incident clearly when you file.
Fake App Pretending to Be a Lender
Some apps have no genuine lending licence or RBI-regulated entity behind them. They may use names that sound like real banks or NBFCs, show professional-looking loan offer screens, and collect KYC documents — only to demand upfront fees, deliver no loan, or disappear after taking money. This is fraud. The complaint belongs with cybercrime authorities. To understand whether the app itself may be a fake, see the guide on how to identify fake loan apps.
Processing Fee or Upfront Charge Scam
A common pattern: the app promises a loan of ₹50,000, instructs the borrower to pay a processing fee of ₹2,000–₹5,000 via UPI, then either never disburses the loan or demands further charges. The UPI transaction reference, recipient ID, and screenshots of the fee demand are critical evidence for this type of complaint.
Disbursal Mismatch and Inflated Repayment Demand
Some apps disburse a smaller amount than agreed — for example, ₹5,000 after deducting platform fees — but then demand repayment of the full advertised amount plus additional charges within days. According to RBI’s digital lending guidelines (rbi.org.in), regulated entities are required to provide a Key Fact Statement showing the actual disbursed amount, interest rate, and charges before any deduction. If no KFS was provided, this is a regulatory violation. If the lender is unregistered, it may constitute fraud.
Threats, Blackmail, Contact Misuse, or Abusive Recovery
If a loan app accessed your contact list, sends threatening messages to your family members, shares edited photographs, or demands payment under threat of public humiliation — this crosses into criminal territory regardless of whether the underlying loan was genuine. These acts may violate the Information Technology Act and RBI’s Fair Practices Code for digital lending. Cybercrime complaints and police FIRs are both appropriate routes.
Genuine Lender Dispute vs Fake App Fraud
A genuine dispute with an RBI-regulated bank or NBFC — for example, a billing error, a wrong EMI demand, or a processing fee not refunded — is handled through the lender’s grievance redressal officer and, if unresolved, through the RBI Complaint Management System. It is not primarily a cybercrime matter. Knowing this distinction prevents you from filing in the wrong place and delaying resolution.
Real Example: Ravi’s Loan App Disbursal Dispute (Illustrative)
Ravi, 29, works as an operations executive in Pune and earns around ₹42,000 per month. In October, he downloaded a quick-loan app that offered an instant personal loan of ₹10,000. The app asked him to pay a one-time processing charge of ₹800 via UPI before disbursal. He paid. The app then disbursed ₹4,200 into his account — not ₹10,000 — deducting platform fees, insurance, and a convenience charge without any prior disclosure. Within eight days, the app sent messages demanding full repayment of ₹10,000 plus a late fee, accompanied by threatening calls to two of his saved contacts.
Here is how Ravi documented his case:
- He saved screenshots of the original loan offer screen (showing ₹10,000), the UPI payment confirmation for ₹800 (with transaction ID and recipient UPI handle), the bank credit message showing ₹4,200 received, and the repayment demand messages.
- He exported his WhatsApp chat with the app’s recovery number as a text file and PDF.
- He noted the app name, Play Store link, and the phone numbers that called his contacts.
- He checked the app’s KFS — there was none, which he screenshot as well.
Ravi filed a complaint on cybercrime.gov.in under financial fraud and separately reported the contact harassment. He did not pay the ₹10,000 demand, but he did not ignore the situation either — he sought written clarification from the app on its lending entity details. This example is illustrative only. Whether any specific demand is legally valid depends on facts that a qualified person would need to assess.
Evidence Checklist Before Filing Your Complaint
Collecting this evidence before you uninstall the app or delete messages can significantly strengthen your complaint. Do not fabricate, edit, or crop out any details — submitting altered screenshots can undermine your case.
| Evidence Type | Example to Save | Save Format |
|---|---|---|
| App name, store link, version | Screenshot of Google Play / App Store page with name, developer, and rating | Screenshot + text note |
| Loan offer screen | Screenshot showing approved amount, tenure, and stated rate | Screenshot |
| KFS or loan agreement | In-app document showing disbursal amount, charges, rate — or note its absence | Screenshot or PDF |
| Disbursal proof | Bank SMS or UPI credit notification showing amount, date, time | Screenshot |
| Processing fee payment | UPI confirmation with transaction ID, recipient UPI handle, amount, date | Screenshot + bank statement |
| Repayment demand | In-app screen or message showing demand amount and deadline | Screenshot |
| Threat or harassment messages | WhatsApp messages, SMS, or calls from unknown numbers with threatening content | Exported chat + screenshot |
| Contact misuse proof | Screenshots of messages sent to your contacts by the app or its agents | Screenshot |
| App permissions screen | Settings screenshot showing contacts, gallery, camera access granted | Screenshot |
| Previous repayment records | UPI confirmations or bank transfers showing amounts already paid, with dates | Bank statement + screenshots |
You should also check whether any bank or NBFC name is mentioned in the app, the loan agreement, or the KFS. Use the guide on how to check RBI app status to verify whether any named lender is genuinely registered with the RBI.
How to Document the Money Flow
When writing your complaint, a clear money flow summary helps investigating authorities understand your case quickly. Here is a documentation structure you can use — this is not a legal format, just a practical organiser.
Net Position = Amount Received − Amount Already Repaid − Processing Fee Paid
Where: Amount Received = what actually arrived in your bank account | Amount Already Repaid = total of all UPI or bank payments made to the app | Processing Fee Paid = any upfront charges you paid before or during disbursal
| Item | Ravi’s Illustrative Figures | Your Actual Figures |
|---|---|---|
| Loan amount promised by app | ₹10,000 | ₹ ___ |
| Processing fee paid upfront (UPI) | ₹800 | ₹ ___ |
| Amount actually disbursed to bank | ₹4,200 | ₹ ___ |
| Amount repaid so far (with dates) | ₹0 (repayment not yet made) | ₹ ___ |
| Amount demanded by app now | ₹10,000 + late fee | ₹ ___ |
| Difference from actual receipt | ₹5,800 above disbursed amount | ₹ ___ |
Fill in your actual figures from bank records and screenshots. Keep this summary with your complaint file. These figures are for documenting your experience — do not present them as legal proof of any specific liability without professional guidance.
Complaint Channel Comparison: Cybercrime Portal vs RBI vs Sachet
| Channel | Use When | Not Best For |
|---|---|---|
| cybercrime.gov.in | Online fraud, money transferred to fraudsters, blackmail, threats, contact harassment, edited photo misuse | Pure billing disputes with verified regulated lenders |
| 1930 cybercrime helpline (verify current instructions) | Recent financial fraud where money was just lost and bank freeze may help | Older complaints, non-financial harassment, or regulatory grievances |
| RBI Complaint Management System (rbi.org.in) | Regulated bank or NBFC has violated fair practice rules, KFS was not provided, or recovery conduct is abusive | Fake or unregistered apps with no real lender behind them |
| Sachet portal (sachet.rbi.org.in) | Suspicious or unregistered financial entity, ponzi-type scheme, or unlicensed lending activity | Confirmed cybercrime situations requiring police involvement |
| Local cyber police station | Follow-up on cybercrime complaint, urgent situations, FIR for blackmail or physical threats | Online filings where cybercrime.gov.in is sufficient |
No single channel guarantees a specific outcome. In many loan app fraud situations, more than one channel may be relevant. File through the channel that best matches your primary issue first, then escalate through others where the facts support it.
money was transferred to a fraudulent account in the last few days — call 1930 (verify current process) and file on cybercrime.gov.in as a priority.
you are receiving threats, blackmail messages, or harassment calls — save all messages first, then file under cybercrime harassment/cyberbullying category on the national portal.
the app names a real bank or NBFC as the lender — verify the entity on rbi.org.in, then contact that lender’s grievance redressal officer separately from the cybercrime complaint.
the lender appears suspicious, unregistered, or unlicensed — report through sachet.rbi.org.in in addition to cybercrime.gov.in.
your contacts are being messaged or your photos are being misused — lodge an FIR at your nearest police station or cyber cell as well, since this may constitute a cognizable offence.
you have a genuine repayment dispute and the lender is verified and regulated — ask for a written loan account statement from the lender before filing a complaint anywhere.
you are certain that fraud or a crime has occurred — do not assume the recovery contact is fraudulent if the lender is actually a regulated entity. Verify first, then decide your complaint route.
Common Mistakes to Avoid
Deleting Messages Before Saving Them
The most common and most damaging mistake is deleting WhatsApp chats, SMS, or call logs from the loan app’s number in a panic. Without this evidence, the complaint becomes very difficult to substantiate. Export WhatsApp chats to a PDF or email before doing anything else.
Paying Fresh “Settlement” Money to Unknown Callers
Fraudulent recovery agents often call borrowers demanding a lump-sum “settlement” or “NOC release fee” via UPI to a new number. This money goes directly to fraud accounts. Paying once rarely stops the harassment — it frequently invites further demands. Do not transfer money to any number that is not the official, verifiable lender account.
Sharing Documents, OTPs, or Permissions Under Pressure
If someone calls claiming to be from a “cybercrime cell,” “RBI,” or “loan resolution officer” and asks for your Aadhaar number, PAN image, bank OTP, or access to your phone — this is itself a fraud. No official agency asks for OTPs or bank passwords over the phone. Sharing these can result in account compromise on top of the original problem.
Posting Screenshots Publicly on Social Media
It is understandable to want public support when facing harassment. But posting screenshots with personal details, phone numbers, and UPI IDs publicly can attract scammers posing as “helpers,” complicate the investigation, and expose additional personal information. For guidance on handling threats specifically through WhatsApp, see the guide on WhatsApp loan app threats.
Filing Only One Complaint and Assuming It Is Complete
Cybercrime complaints can take time to process. Filing on cybercrime.gov.in is the right first step, but if the situation involves a regulated lender’s misconduct, a suspicious entity, or contact misuse, additional channels — the lender’s grievance officer, Sachet, or a local FIR — may also need to be used in parallel.
Assuming the Recovery Call Is Always Fraudulent
If you took a loan through an app linked to a genuine NBFC or bank, that lender’s recovery team may contact you legitimately for overdue EMIs. Before treating every recovery contact as fraud, verify whether a real regulated entity is named in your loan agreement or KFS, and check the official lender website for their grievance contact.
Uninstalling the App Without Documenting First
Uninstalling removes the app’s interface, notifications, in-app loan details, and document history. Take screenshots of every screen you can access — loan account summary, repayment schedule, contact details, KFS, Terms — before removing the app from your phone.
When a Cybercrime Complaint May Not Be the Right First Step
A cybercrime complaint is appropriate for fraud, blackmail, threats, and contact misuse. But it may not be the primary route in every situation involving a loan app.
If you have a genuine repayment dispute with a verified, RBI-regulated lender — for example, a disagreement about the EMI amount, a processing fee deducted incorrectly, or a payment not reflected — the lender’s grievance redressal officer and the RBI Complaint Management System are the correct channels, not the cybercrime portal.
If your credit report has been incorrectly updated after repayment, that is a bureau-level correction matter handled through CIBIL, Experian, Equifax, or CRIF High Mark — not a cybercrime complaint.
If you are in an immediate physical danger situation — the threat has moved beyond digital messages to actual intimidation in person — contact emergency police at 112 before filing an online complaint.
If the dispute involves complex contractual or civil issues, such as disputed loan terms or contested ownership of funds, a qualified legal professional is better placed to advise than an online complaint portal.
If any of these apply to your situation, it may be worth exploring other options before committing.
Official Rules and Where to Verify
The following official sources are relevant to loan app fraud complaints and borrower safety in India. Verify current process details, helpline numbers, and complaint instructions directly from each source before acting:
- National Cyber Crime Reporting Portal — cybercrime.gov.in — primary official portal for filing cybercrime complaints including online financial fraud, blackmail, threats, and contact/photo misuse.
- Cybercrime helpline 1930 — verify current instructions and availability at cybercrime.gov.in before calling, as helpline processes and hours may be updated.
- Reserve Bank of India — rbi.org.in — source for digital lending guidelines, the RBI Complaint Management System, the list of regulated entities, and borrower-protection rules including the Fair Practices Code.
- RBI Sachet Portal — sachet.rbi.org.in — use for reporting suspicious or unregistered financial entities, unauthorized deposit-taking, or doubtful lending schemes.
- Local state cyber police — check your state police or cyber cell website for state-specific complaint registration, FIR process, and follow-up procedures.
For the official RBI framework governing how digital lenders are permitted to operate, including rules on KFS, consent, data access, and grievance handling, see the guide on digital lending rules.
Rules, rates, charges, and eligibility conditions can change. Always verify current details from the official source, lender, or relevant regulator before making a financial decision.
Expert Tips
- Write a timeline before filing. Prepare a chronological list: date the app was installed, date the loan was promised, date money arrived, date the processing fee was paid, dates of each threatening message or call. A clear timeline makes the complaint easier to understand and follow up on.
- Use the right language in your complaint description. Describe what happened factually — “I received a credit of ₹4,200 to my account on [date] after paying ₹800 as processing fee on [date]. The app is now demanding ₹10,000 and has sent threatening messages to my contacts.” Avoid emotional language or conclusions like “this is definitely illegal.”
- Keep evidence in a separate folder. Create a named folder on your phone or cloud account — for example, “Loan App Evidence October 2025” — with all screenshots, chat exports, and bank records. Organized evidence is easier to upload and retrieve later.
- Do not use middlemen or social media “helpers.” Several social media accounts offer to recover money or resolve loan app fraud for a fee. These are frequently secondary scams targeting distressed borrowers. Use only cybercrime.gov.in, 1930, RBI channels, and official police.
- Follow up using your complaint number. After filing on cybercrime.gov.in, note the complaint acknowledgement number and follow up through the portal’s status tracking feature. For helpline calls, note the date, time, and any reference number given.
- Verify the lender before deciding on the dispute route. A loan app can be a legitimate front-end for a genuine NBFC. Verify the NBFC name on rbi.org.in. If the NBFC is registered, the recovery misconduct issue goes to the NBFC’s grievance officer first, not just to cybercrime.
- Keep the complaint clean. File one clear complaint per incident. Multiple complaints filed simultaneously across different categories for the same event can cause coordination delays. Describe the primary issue accurately and add secondary channels only where genuinely applicable.
Frequently Asked Questions
How do I file a cybercrime complaint against a loan app in India?
Go to cybercrime.gov.in and select the relevant complaint category — financial fraud or online harassment, depending on what happened. Create an account or log in, fill in the incident details, upload your screenshots and transaction proof, and submit. Save the complaint acknowledgement number. Verify current portal steps before filing, as the interface and categories may be updated.
Can I call 1930 for loan app fraud?
The 1930 helpline is operated for cybercrime financial fraud reporting and may be useful if money was recently transferred to a fraudulent account. Call availability, response scope, and exact process should be verified at cybercrime.gov.in before relying on this route, as helpline details can change.
What proof is needed for a loan app fraud complaint?
You will typically need: the app name and store link, screenshots of the loan offer and disbursal, UPI transaction reference numbers for any money paid, screenshots of threatening or abusive messages, call logs if relevant, and a written description of the timeline. The more specific your evidence, the clearer the complaint will be.
Should I complain to the cybercrime portal or RBI first?
For fraud, blackmail, threats, contact misuse, and financial cybercrime — file on cybercrime.gov.in first. For grievances against a verified, RBI-regulated bank or NBFC — raise the issue with that lender’s grievance officer first, and then escalate to the RBI if unresolved. Both routes may be needed in the same situation depending on the facts.
What should I do if a loan app is threatening my contacts?
Save every threatening message sent to you and, if visible, messages sent to your contacts. File a cybercrime complaint under harassment/cyberbullying. Also consider lodging an FIR at your nearest police station or cyber cell, since this conduct may constitute a criminal offence under the Information Technology Act. Warn your contacts calmly without escalating panic.
Can cybercrime police recover money lost to a fake loan app?
In some cases, if the complaint is filed quickly and money can be traced to an active account, authorities may be able to freeze and recover funds. But this is not guaranteed, and outcomes depend on the speed of filing, the traceability of the account, and the investigative process. No complaint portal or helpline guarantees money recovery. The primary goal of filing is to report the offence, create an official record, and trigger the appropriate investigation.
Should I uninstall the loan app before filing a complaint?
No — not until you have saved all evidence. Take screenshots of every screen inside the app: loan offer, repayment schedule, contact details, KFS, and any in-app messages. Note the app developer name, version, and Play Store or App Store link. After saving everything, you can revoke app permissions and, if needed, uninstall the app.
What if the loan app names a real bank but the behaviour is abusive?
Verify the bank’s name on rbi.org.in. If it is genuinely regulated, raise a formal grievance through the bank’s own grievance redressal officer. If the bank does not resolve the complaint within the stipulated time, escalate to the RBI Complaint Management System. Abusive recovery conduct by a regulated entity is a separate regulatory issue from cybercrime — both paths may need to be used simultaneously.
Is it safe to post evidence on social media to expose the app?
It is generally not advisable to post personal screenshots, phone numbers, or UPI details publicly. Public exposure can attract secondary fraudsters posing as helpers, and it may complicate the official complaint process. File through official channels first. If you want to share a warning publicly, do not include your own personal financial details or the exact transaction information.
What happens after I file a cybercrime complaint?
After submission, you receive a complaint acknowledgement number. Authorities may contact you for additional information. The investigation process, timeline, and outcome depend on the nature of the complaint and the evidence available. Follow up through the portal’s complaint status feature. There is no guaranteed action timeline — verify current response expectations at cybercrime.gov.in.
Final Verdict
If a loan app has taken your money through fraud, sent threats, misused your contacts, or demanded inflated repayments — the most important thing you can do right now is save your evidence before deleting anything. A cybercrime complaint for loan app fraud belongs primarily on cybercrime.gov.in, with the 1930 helpline as an urgent parallel step if money was very recently lost. If a regulated lender is involved, their grievance officer and the RBI are the right escalation channels for the misconduct. If the entity appears unregistered or suspicious, add a Sachet report as well. Do not pay extra money under threat, do not share documents with unknown callers, and do not assume the situation resolves itself. Official channels, organized evidence, and a calm approach give you the best chance of being taken seriously. Always verify the latest rules, charges, and terms from the relevant official source or provider before making a financial decision.
This article is for educational purposes only and should not be treated as personalised financial, credit, tax, or legal advice. Rules, rates, charges, eligibility criteria, and product terms can vary by provider and may change over time. Please verify current details from official sources, the relevant provider, or a qualified professional before making any financial decision.
Arjun writes clear borrower-safety guides on digital loan apps, RBI digital lending rules, KFS, APR, LSPs, loan app harassment, cybercrime complaints, CIBIL impact, and safer borrowing choices. He focuses on helping Indian borrowers understand risks, protect their data, compare lenders carefully, and use official complaint channels when needed.