
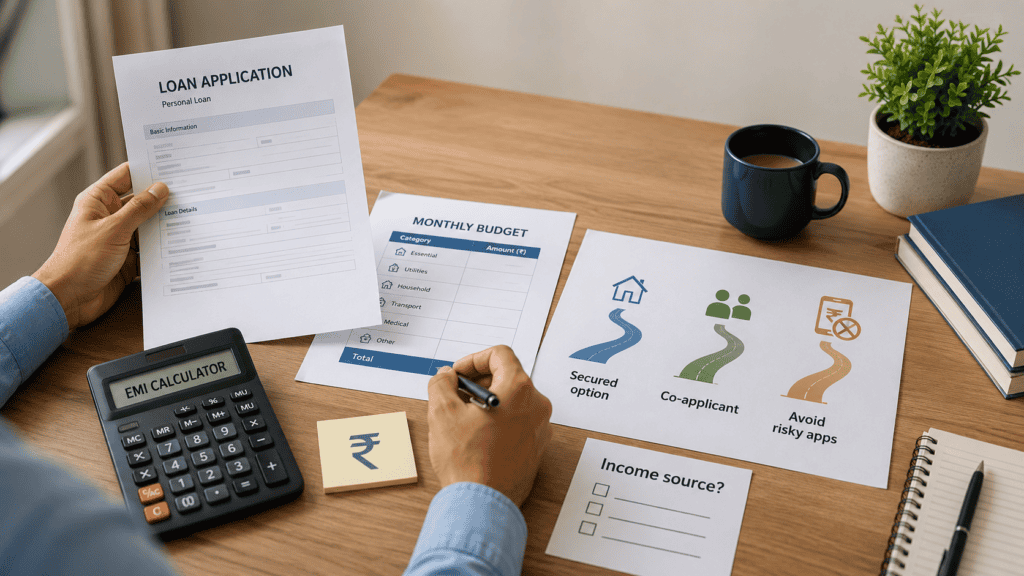
You lost your job, the bills haven’t stopped, and you’re staring at loan apps and bank websites wondering if any of them will actually say yes. A loan for unemployed people in India is genuinely hard to get if you’re applying the way a salaried person would — most lenders are built around one question: can you repay this every month, on time, for the next few years? Without a salary slip, that question gets harder to answer.
But difficult is not the same as impossible. Gold sitting in a locker, a fixed deposit, a working spouse willing to co-sign, or a small business idea can all change what a lender sees when they look at your file. This guide walks through what’s realistic, what’s risky, and when it’s smarter to wait than to borrow. One thing first: if an app or website promises a “loan without job, 100% guaranteed approval,” that’s not a shortcut — it’s usually a warning sign.
Quick Answer: Can You Get a Loan Without a Job in India?
A loan for unemployed people is difficult without income proof, but not impossible. In India, realistic options may include a gold loan, loan against FD, a co-applicant loan, or a Mudra loan for business use. Before borrowing an illustrative ₹50,000, check EMI affordability, collateral risk, CIBIL impact, and lender charges.

Immediate Action Steps Before You Apply Anywhere
Step 1 — Decide if this need can wait
Not every expense is a today problem. If you can delay two to three weeks without real consequence, you buy time to compare options instead of grabbing the first offer.
Step 2 — Map your repayment source for the next 3–6 months
Before applying anywhere, write down — honestly — where the EMI money will come from each month. Severance pay, a spouse’s salary, freelance income, or family support all count. “I’ll find a job soon” does not count as a repayment plan.
Step 3 — Check your CIBIL report and existing dues
Pull your credit report and note any existing EMIs or credit card dues. A new loan on top of unpaid existing debt is the fastest way into a debt spiral.
Step 4 — Compare secured, co-applicant, and scheme options side by side
Don’t apply to the first lender that responds. Lay out gold loan, FD-backed loan, co-applicant loan, and Mudra loan (if business-related) against each other before choosing.
Step 5 — Reject any advance-fee or guaranteed-approval offer
No legitimate bank or RBI-registered NBFC asks for a fee upfront just to “process” or “guarantee” your loan before sanction. If you’re asked to pay first, stop.
Key Takeaways
- Unsecured personal loans are difficult to get without income proof because lenders cannot verify your monthly repayment capacity.
- Secured loans — gold, FD, LIC, mutual funds, or property — are more realistic without a job, but the asset is at risk if EMIs are missed.
- A Mudra loan is meant for income-generating business activity, not casual personal expenses, and still goes through normal bank assessment.
- Loan apps offering instant cash with no income check and no CIBIL check carry real fraud and harassment risk — verify the lender before applying.
- A co-applicant with stable income can significantly improve approval chances on an otherwise unsecured personal loan.
- Borrow only if you can identify a real repayment source for the next several months — not “I’ll manage somehow.”
- Interest rates, processing fees, loan-to-value limits, and scheme eligibility change often — always verify current figures from RBI, the lender, or the relevant scheme before applying.
Key Facts at a Glance
| Question | Realistic Answer | What to Check |
|---|---|---|
| Can unemployed people get a loan? | Rarely for unsecured personal loans; more realistic with collateral or a co-applicant | Lender’s specific eligibility policy |
| Most realistic options | Gold loan, loan against FD, co-applicant personal loan, Mudra (business use) | Current LTV, rates, and fees — confirm before applying |
| Most risky options | Unverified loan apps, advance-fee offers, “no income, no CIBIL” ads | Lender’s RBI registration and digital lending compliance |
| Documents likely needed | ID/address proof, bank statements, collateral papers if secured, co-applicant income proof if joint | Exact document list with the specific lender |
| When not to borrow | No repayment source, existing dues unpaid, non-essential expense | Your own 3–6 month cash flow estimate |
Why a Loan for Unemployed People Is Difficult — And What Lenders Actually Check
“Unemployed” isn’t one situation. A person between jobs with a severance payout, a self-employed person without formal income papers, and someone with no income source at all face very different odds — even though all three might search for the same loan for unemployed people. Lenders don’t reject applications because they dislike the word “unemployed.” They reject them because they can’t answer one question: will the EMI get paid?
What lenders are really checking
For a regular personal loan, a lender typically looks at your bank statements, your credit report, and your FOIR — Fixed Obligation to Income Ratio, which is roughly how much of your monthly income already goes toward existing EMIs and debts. Without a salary credit showing up month after month, FOIR becomes difficult to calculate, and that uncertainty is what drives rejections.
Your low credit profile or a thin credit history compounds the problem — a lender weighing an unclear income picture against a weak CIBIL report has very little to work with. This is part of why a broader loan without a job strategy usually has to lean on something other than income alone.
Unsecured vs secured: the real dividing line
An unsecured personal loan is approved almost entirely on your promise to repay, backed by income and credit history. A secured loan is backed by an asset — gold, an FD, LIC policy, mutual fund units, or property — that the lender can recover value from if you default. Without income, secured options shift the lender’s risk from “will this person repay?” to “is this asset worth more than the loan?” — a much easier question to answer, which is why they tend to be more accessible.
How a co-applicant or guarantor changes things
Adding a co-applicant with stable income — a spouse, parent, or sibling — gives the lender a second, verifiable repayment source. The loan is assessed partly on the co-applicant’s income and credit profile, not just yours. A guarantor works differently: they don’t receive the loan amount but become legally responsible if you default, so most people only ask someone they trust deeply and have discussed the risk with openly.
According to RBI’s regulatory framework for lending and digital lending guidelines, all RBI-registered lenders are expected to assess repayment capacity transparently and disclose loan terms upfront through a Key Fact Statement — a useful checkpoint regardless of which option you pursue.
Real Example: Rohit’s Three Options After Losing His Job
Rohit, 31, worked in a private-sector marketing role in Pune until his company restructured and let him go. He has ₹35,000 in savings, one credit card bill of about ₹18,000 due, and an unexpected family medical expense pushing his need to roughly ₹50,000 — illustrative figure, not a quoted offer.
His three realistic paths look very different. Option A — applying for an unsecured personal loan — carries high rejection risk; without a salary credit in his bank statement, most lenders would likely decline or offer a very small amount at a higher rate. Option B — taking a loan against the ₹40,000 worth of gold jewellery his family owns — is more likely to be approved, assuming an illustrative loan-to-value rate, but his family’s gold is now at risk if he can’t repay on schedule. Option C — borrowing ₹20,000 from his brother interest-free and trimming discretionary spending for two months — avoids new EMI pressure entirely while he job-hunts.
The insight that matters here: the “easiest to get” option and the “safest” option are often not the same thing — Rohit’s real decision is about which risk he’s more willing to carry, not which application is fastest.
Eligibility and Requirement Checklist Before You Apply
Lenders ask for documents to build a picture of who you are and what you can repay — having the documents ready doesn’t guarantee approval, but missing them guarantees delay or rejection.
| Checklist Item | Why It Matters | Ready / Not Ready |
|---|---|---|
| PAN, Aadhaar, address proof | Basic identity verification required by every regulated lender | Self-check |
| Bank statements (6 months) | Shows any income flow — freelance, rental, severance, family transfers | Self-check |
| CIBIL report and active dues | Reveals existing obligations and repayment history | Self-check |
| Collateral documents (if secured) | Gold purity certificate, FD receipt, LIC policy, or property papers | Self-check |
| Co-applicant income proof (if joint) | Salary slips or ITR of the co-applicant strengthen the application | Self-check |
If you’re missing a salary slip entirely, it helps to understand what alternative documents some lenders accept — see this guide on a personal loan without a salary slip. According to TransUnion CIBIL, your credit report also reflects recent hard inquiries, so spacing out applications matters more than it might seem.
How to Calculate the Real Cost of a Small Loan
Even a modest loan can feel heavier than expected once interest and fees are added — especially without a steady income to absorb it. Take an illustrative ₹50,000 loan at an assumed reducing-balance rate, compared across tenures:
EMI = [P × r × (1+r)^n] ÷ [(1+r)^n − 1]
Where: P = principal loan amount | r = monthly interest rate | n = number of months
| Tenure | Illustrative EMI | Illustrative Total Repayment |
|---|---|---|
| 6 months | Higher EMI, lower total interest | Principal + smallest total interest |
| 12 months | Moderate EMI | Principal + moderate total interest |
| 24 months | Lower EMI, higher total interest | Principal + highest total interest |
The pattern that matters: a lower EMI on a longer tenure feels easier month to month, but it usually means paying more in total interest over the life of the loan — and a processing fee, where applicable, adds to that total cost regardless of tenure. Always ask for the total repayment figure, not just the EMI, before agreeing to anything.
Comparison: Realistic Options for Unemployed Borrowers
| Option | Approval Difficulty | Main Risk |
|---|---|---|
| Gold loan | Easier | Loss of pledged gold on default |
| Loan against FD | Easier | FD gets locked/liquidated on default |
| Loan against LIC / mutual funds / property | Moderate | Asset valuation and processing time vary |
| Co-applicant personal loan | Moderate | Co-applicant becomes equally liable for default |
| Mudra / business loan | Conditional | Only for verified business purpose, not personal cash need |
| Unverified loan apps | Risky | Fraud, harassment, very high effective cost |
For a closer look at gold-backed borrowing specifically, see gold loan without income proof. Loan-to-value limits, gold loan rates, and Mudra loan categories all change with RBI policy and scheme updates, so treat the figures above as directional, not fixed.
Safety Checklist Before You Borrow
Safety Checklist
- Avoid any lender or app asking for a processing fee before sanction is even confirmed.
- Avoid apps demanding access to your contacts, gallery, or call logs — legitimate lenders don’t need this.
- Verify the lender’s RBI registration and check for a proper Key Fact Statement before signing anything.
- Don’t borrow if you can’t currently name where next month’s EMI will come from.
- Don’t apply to five apps at once hoping one says yes — each hard inquiry affects your credit report.
RBI’s digital lending guidelines specifically caution against lending apps that bypass formal disclosure norms — that’s the standard to hold any app you’re considering against.
How to Decide What’s Right for You
you have gold, an FD, or another asset and a realistic repayment source — a secured loan against that asset is worth comparing across two or three lenders.
a family member with stable income is willing to co-apply — a co-applicant personal loan likely has better odds than applying alone.
you’re planning a small income-generating activity, not personal spending — Mudra loan eligibility is worth checking through a participating bank.
you expect a job offer or salary credit within a few weeks — waiting often costs less than borrowing at a higher rate now.
you have any clear repayment source — avoid taking on new EMI even if an app says you’re “pre-approved.”
you’ve checked the lender’s RBI registration and KFS — don’t proceed, regardless of how fast the approval looks.
This decision works alongside comparing a loan against FD against other secured routes — the right comparison depends on which asset you actually have available, according to Mudra’s published scheme purpose for the business-loan route.
Common Mistakes to Avoid
Applying to many lenders or apps at once
Submitting five or six applications hoping one approves you.
Each application can trigger a hard inquiry on your credit report, and multiple inquiries in a short window signal credit-hungry behaviour to lenders — making approval harder, not easier.
Shortlist two or three realistic options based on your actual profile before applying.
Believing “no income, no CIBIL, guaranteed approval” ads
Trusting marketing that promises approval regardless of your financial situation.
Legitimate lenders always assess repayment capacity; offers that skip this step are often unregistered apps charging very high effective rates or running fee scams.
Treat “guaranteed approval” language itself as the warning sign.
Ignoring total cost and processing fees
Focusing only on the EMI amount, not the total repayment.
A low EMI on a long tenure can mean paying significantly more in total interest, plus a processing fee that’s often a percentage of the loan amount — confirm this with the specific lender.
Always ask for the total repayment figure before agreeing to terms.
Pledging family assets without a repayment plan
Putting up a parent’s gold or FD without first confirming how the EMI will be paid.
If repayment fails, the asset — often something with emotional as well as financial value — is at risk, and the consequences fall on the whole family, not just you.
Get explicit agreement and a written repayment plan before pledging any shared family asset.
Taking a business scheme loan for personal use
Using a Mudra or similar business-purpose loan to cover personal expenses.
These schemes require the loan to fund income-generating business activity; misrepresenting the purpose can create documentation and compliance problems later.
Apply for business schemes only if you have a genuine, demonstrable business plan.
Going straight to high-cost unsecured options out of urgency
Choosing the fastest-approving app instead of comparing alternatives.
Speed often correlates with higher effective interest rates and less transparent fee structures, which compounds financial stress rather than relieving it.
Spend even one extra day comparing secured and co-applicant alternatives before committing.
Skipping the credit report check
Applying without first knowing your own CIBIL score and report status.
You may be rejected for a reason — like an old unpaid due — that you weren’t even aware of, wasting an inquiry and time.
Check your loan rejection reasons guide and your credit report before applying anywhere.
When This May Not Be the Right Choice
If you have no predictable income or repayment source for the next several months, taking on new EMI obligations can deepen financial stress rather than solve it.
If you already have unpaid EMIs or credit card dues, adding another loan on top often accelerates a debt spiral rather than buying relief.
If the need is for non-essential spending rather than an emergency, it’s worth exploring non-loan alternatives first.
If pledging a family asset like gold or an FD would seriously harm the household if lost, the risk may outweigh the benefit of fast cash.
If any of these apply to your situation, it may be worth exploring other options before committing.
Official Rules and Where to Verify
Before acting on anything in this guide, confirm current figures and rules directly from these official sources:
- RBI (rbi.org.in) — for regulated lending standards, digital lending guidelines, and borrower disclosure norms.
- TransUnion CIBIL (transunioncibil.com) — for your credit report, score, and inquiry history.
- Mudra (mudra.org.in) — for current business-loan scheme categories, limits, and eligibility.
- Udyam Registration (udyamregistration.gov.in) — for MSME/self-employment registration if you’re pursuing a business-purpose loan.
- The specific bank or NBFC’s official website — for current rates, fees, loan-to-value ratios, and documentation requirements.
Rules, rates, and charges on this topic can change with RBI policy or lender updates. Always verify current figures directly from the official source or the lender before making any borrowing decision.
Expert Tips
- Before applying anywhere, write down your actual repayment source for the next 3–6 months — if you can’t name one, that’s information, not failure.
- If you’re considering a secured loan, ask specifically what happens to your asset at each stage of missed payment, not just at final default.
- Limit yourself to two or three targeted applications rather than applying broadly — your credit report tracks every inquiry.
- Always request the Key Fact Statement (KFS) and compare total repayment cost, not just the EMI, across any options you’re weighing.
- If a relative agrees to be a co-applicant or guarantor, have an honest conversation about what happens if you can’t pay — before signing, not after.
- Never pay an upfront “processing” or “guarantee” fee to an app or website before a loan is formally sanctioned through verifiable channels.
Frequently Asked Questions
Can an unemployed person get a personal loan in India?
It’s possible but difficult for a regular unsecured personal loan, since lenders rely heavily on income proof. Secured options or a co-applicant with stable income improve the odds considerably.
Which loan is easiest to get without a job?
Secured loans — particularly a gold loan or a loan against an FD — tend to be more accessible than unsecured personal loans, since the lender’s risk is backed by an asset rather than your income alone.
Can I get a loan without income proof?
Some secured lenders may not require traditional income proof if you’re pledging gold, an FD, or another asset, but you’ll still need to show some realistic repayment plan and complete standard KYC documentation.
Can I get a loan if I have no salary but good CIBIL?
A strong CIBIL score helps, but most lenders still want to see some income source or repayment capacity alongside it — a good score alone rarely overrides the absence of any income signal.
Are loan apps safe for unemployed people?
Not automatically. Many unregistered apps specifically target borrowers with no income using “guaranteed approval” claims, then charge very high fees or use harassment-style recovery tactics. Verify RBI registration and check for a proper KFS before using any app.
Can unemployed people apply for Mudra loans?
Mudra loans are meant to fund income-generating business activity, not personal expenses — so eligibility depends on having a genuine business plan that a participating bank is willing to assess and finance, not on employment status alone.
Is a gold loan better than a personal loan without a job?
It’s often more accessible since it’s secured by an asset, but “better” depends on whether you’re comfortable with the risk of losing pledged gold if repayment fails — that trade-off is worth weighing carefully, not assumed.
What happens if I can’t repay a secured loan?
The lender can recover the loan by liquidating or auctioning the pledged asset — gold, FD, or property — following their disclosed recovery process, which is why a clear repayment plan matters before pledging anything.
Is it safe to take a loan to repay another loan?
Generally risky without a clear, written plan — borrowing to repay borrowing without a new income source usually compounds debt rather than resolving it.
Final Verdict
A regular unsecured loan for unemployed people remains genuinely difficult to get in India, because most lenders assess repayment capacity through income they can verify. Secured options — gold, FD, LIC, mutual funds, or property — and co-applicant loans are more realistic paths, but each carries its own risk that deserves honest evaluation, not urgency-driven decisions. Government schemes like Mudra exist for business purposes and go through normal bank assessment — they aren’t a shortcut to personal cash. If you can’t currently identify a repayment source, the safest move may be to wait, lean on family support, or trim expenses rather than take on new EMI. Always verify the latest rates and terms from the lender or official RBI sources before applying for any loan.
This article is for educational purposes only and should not be treated as personalised financial, credit, or legal advice. Interest rates, processing fees, eligibility criteria, and loan terms vary by lender and can change with RBI policy or lender updates. Please verify current rates and terms directly with the lender or from official RBI sources, or consult a qualified professional, before applying for or accepting any loan.
Rohan writes practical personal loan guides for Indian borrowers, focusing on eligibility, EMI planning, lender charges, CIBIL impact, borrower rights, and safer borrowing choices. His writing helps readers compare options calmly, avoid costly mistakes, and understand loan terms before applying.