

When you need money urgently, the first question that comes to mind is usually: which option will approve fastest? But the faster question — and the safer one — is: who is actually lending me the money, and what happens if something goes wrong? Many borrowers in India today apply through a loan app without realising that the app may not be the lender at all. The actual money may be coming from a bank or NBFC operating behind the app’s interface. Understanding the difference between a bank, an NBFC, and a loan app before you apply is not a technical exercise. It is a basic safety check. This article explains each option clearly — including what a Lending Service Provider (LSP) is, why the Key Fact Statement (KFS) and Annual Percentage Rate (APR) matter, and what to do if something goes wrong — so you can borrow with your eyes open.
Quick Answer: Bank vs NBFC vs Loan App
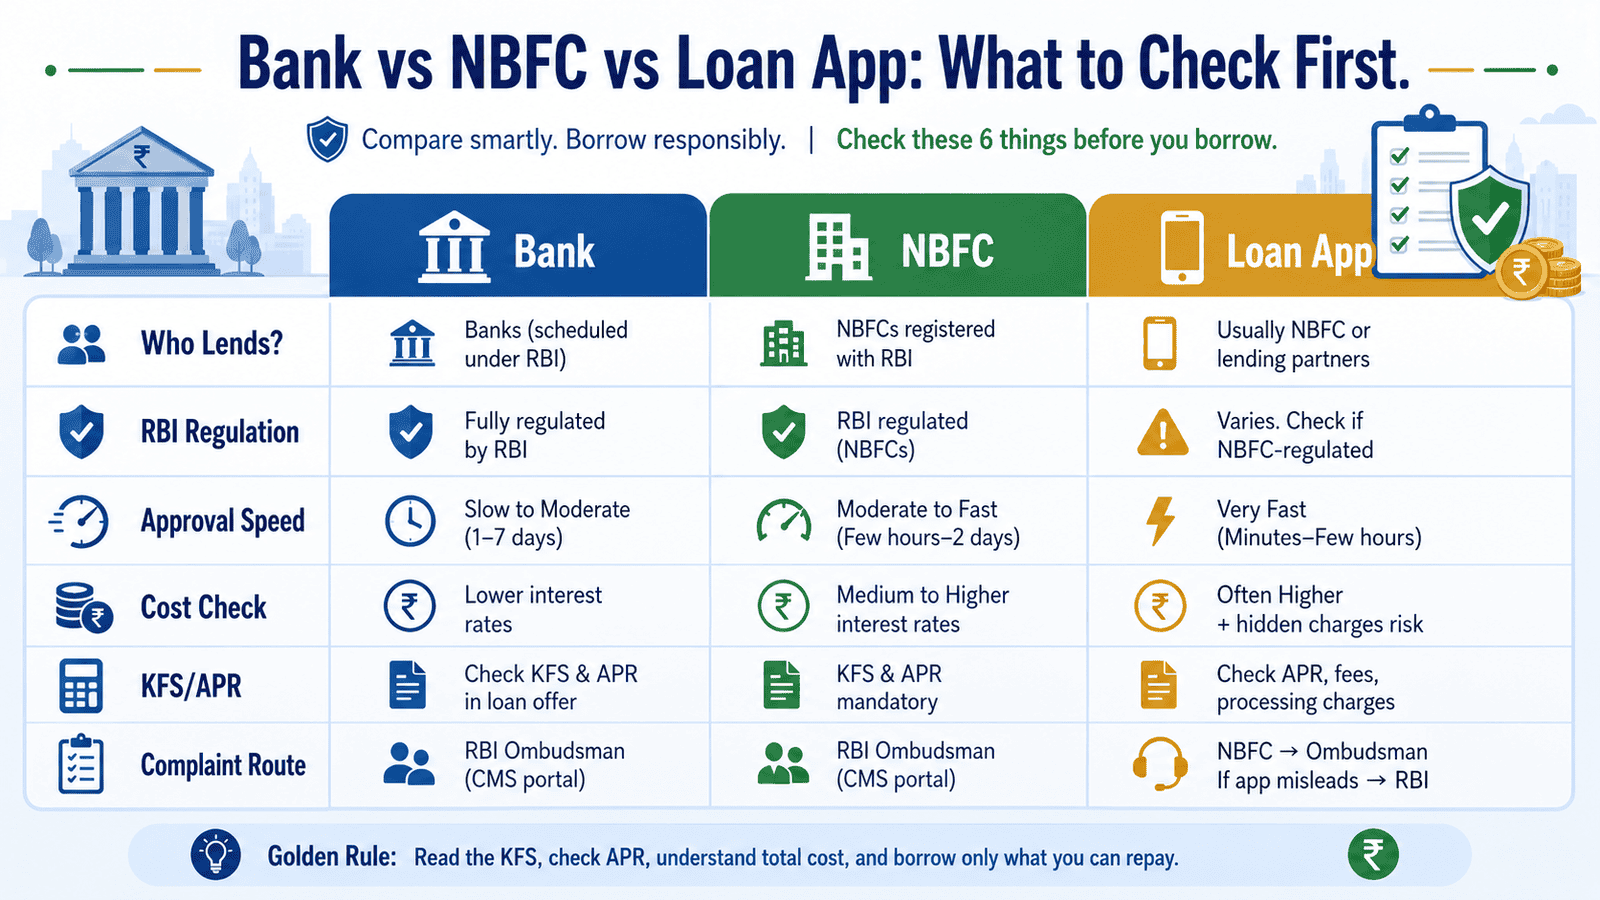
Bank vs NBFC vs loan app means comparing three borrowing routes: a bank directly lends, an NBFC directly lends, while a loan app may be only a digital platform or LSP. Before applying, identify the RBI-regulated entity, read the KFS, compare APR, and check the complaint route.
Key Takeaways
- A loan app is not always the lender — it may be a digital front-end operated by a Lending Service Provider (LSP) connected to a bank or NBFC that is the actual regulated lender.
- Banks are regulated by RBI and tend to have stricter eligibility — typically a strong CIBIL score, stable income, and full documentation — but may offer more predictable processes and complaint channels.
- NBFCs are also regulated by RBI and can be more flexible on eligibility, but interest rates and processing charges may be higher for borrowers with weaker credit profiles.
- Loan apps backed by unverified or unregistered entities carry the highest borrower risk — including data misuse, harassment, and hidden charges — so the regulated lender identity must always be verified before applying.
- Before accepting any digital loan, read the KFS (Key Fact Statement) which must show the APR, total repayment amount, all charges, and grievance contact details — these disclosures are required under RBI’s Digital Lending Directions.
- Charges, eligibility conditions, interest rates, and complaint routes vary by lender and can change — always verify current terms directly from the lender or official RBI sources before applying.
Bank vs NBFC vs Loan App: Main Comparison
| Factor | Bank | NBFC | Loan App |
|---|---|---|---|
| Who actually lends | The bank directly | The NBFC directly | A bank or NBFC behind the app — verify who |
| RBI regulation | Yes — scheduled bank | Yes — if RBI-registered NBFC | App itself is not a lender — lender must be regulated |
| Approval speed | Days to weeks typically | Often faster than bank | Minutes to hours — but verify before accepting |
| Documentation | Higher — KYC, income proof, bank statements, CIBIL | Moderate — KYC, income proof, bureau check | Minimal at intake — but lender behind app may still run a bureau check |
| Eligibility flexibility | Stricter — salary, CIBIL, employment type matter | Often more flexible for non-traditional profiles | Varies entirely by the actual lender behind the app |
| Interest rate and APR | Typically lower for eligible borrowers — verify current rates | Can be higher depending on risk profile — verify | APR can be significantly high — check KFS before accepting |
| KFS provided? | Required for digital loan offers | Required for digital loan offers | Required — if absent, do not proceed |
| Data permissions risk | Lower — bank app scope is usually narrow | Moderate — depends on the NBFC app | Higher — some apps request contacts, gallery, location beyond what is necessary |
| Grievance channel | Bank’s grievance officer, then RBI Ombudsman | NBFC’s grievance officer, then RBI Ombudsman | Lender’s grievance officer — cybercrime.gov.in for fraud or data misuse |
| Borrower check priority | Verify rate, APR, processing fee, prepayment terms | Verify regulation status, total cost, grievance channel | Verify lender name, regulation, KFS, APR, permissions — before anything else |
Key Facts at a Glance
| Term | What It Means | Why It Matters for You |
|---|---|---|
| Bank | A scheduled commercial bank regulated by RBI that takes deposits and lends money directly | The bank itself is the lender — regulated, with a defined complaint path |
| NBFC | Non-Banking Financial Company — an RBI-registered entity that lends but cannot accept demand deposits like banks | A legitimate lender with its own RBI regulation, but not a bank — terms can vary widely |
| Loan App | A digital application that may be bank-owned, NBFC-owned, or operated by a third-party platform — the app is not automatically the lender | You must look past the app to identify the regulated entity actually lending the money |
| LSP (Lending Service Provider) | A company engaged by a regulated lender to operate the digital front-end, source borrowers, or manage the app interface — but an LSP cannot lend money itself | If you borrow through an app, find out if it is the lender or an LSP — an LSP must be associated with a regulated entity. Learn more about the loan service provider role. |
| KFS (Key Fact Statement) | A standardised document required under RBI’s Digital Lending Directions that shows APR, all charges, total repayment amount, and grievance details before loan acceptance | Do not accept any digital loan without reading the KFS first. See the full Key Fact Statement guide to understand every line. |
| APR (Annual Percentage Rate) | A single percentage figure that captures not only the interest rate but also key charges spread over the loan tenure, giving a fuller picture of borrowing cost | A low advertised monthly rate may hide a high APR once processing fees and other charges are included |
How Borrowing Actually Works Through Each Route
Step 1 — Bank Loan: Direct Regulated Lending
When you borrow from a bank, the bank itself is the lender. It holds a banking licence under RBI regulation, assesses your eligibility — typically based on your CIBIL score, income, employment type, existing EMI obligations, and KYC documents — and disburses the loan amount directly to your bank account. The complaint path is clear: contact the bank’s internal grievance officer first, then escalate to the RBI Integrated Ombudsman Scheme if the issue is unresolved. Banks are familiar institutions, but their eligibility filters can be stricter — particularly for salaried borrowers with a thin credit file, a credit score below what the lender finds acceptable, or a high existing EMI-to-income ratio.
Step 2 — NBFC Loan: Regulated Non-Bank Lender
An NBFC — Non-Banking Financial Company — is a company registered with RBI that can lend money but cannot accept demand deposits the way banks do. NBFCs range from large well-known finance companies to smaller specialised lenders. Many NBFCs process loans faster than banks and may consider borrowers with non-traditional income or a slightly lower credit score, though this flexibility often comes with higher interest rates or charges. The NBFC itself is the lender. If the NBFC is RBI-registered, it falls under RBI’s digital lending rules, has to provide a KFS, and must have a grievance redressal channel.
Step 3 — Loan App: Platform, Lender, or LSP?
This is where most borrowers get confused — and where the safety risk is highest. A loan app can be one of three things: a bank’s own digital app, an NBFC’s own digital app, or a third-party app operated by a Lending Service Provider (LSP). An LSP is a company that partners with a regulated lender to handle the customer-facing side of digital lending — sourcing borrowers, collecting documents, or running the app interface. The LSP is not a lender. It cannot legally disburse money on its own. The regulated bank or NBFC behind it is the actual lender. Understand the full structure of this relationship in the guide to the loan service provider role.
According to RBI’s Digital Lending Directions, regulated entities and their LSP partners are required to disclose the name of the regulated lender in the loan offer, provide a KFS before loan acceptance, disburse funds only to the borrower’s own bank account, and maintain a grievance redressal officer accessible to borrowers. The core safety question before applying through any app is: which RBI-regulated bank or NBFC is the actual lender here?
Who Actually Lends the Money? — Quick Reference
| Borrowing Route | Actual Lender | App or Platform Role |
|---|---|---|
| Bank branch or bank’s own app | The bank directly | The bank’s own interface — lender and platform are the same |
| NBFC’s own app or website | The NBFC directly | The NBFC’s own interface — lender and platform are the same |
| Third-party loan app (LSP-operated) | A bank or NBFC behind the app | The app is the LSP’s front-end — the lender name must be disclosed before you accept |
| Unverified or unregistered app | Unknown or unregulated | High risk — no regulated lender may exist behind it at all |
Real Example: Rahul Compares Three Loan Routes in Pune
Rahul, 29, works as an accounts executive in Pune and earns around ₹48,000 per month. He needs ₹1.5 lakh urgently for a medical expense. He shortlists three options: his salary bank’s personal loan offer, an NBFC he found online, and a fast-approval loan app a colleague mentioned.
His bank offers a personal loan at an advertised interest rate with clear documentation requirements — but the process may take several working days and his CIBIL score of 710 is acceptable but not strong. The NBFC’s offer shows a higher APR once processing charges are added, but the approval timeline is shorter and the eligibility terms are more flexible for his income bracket. The loan app offers approval in minutes — but Rahul notices the app does not show a lender name on the offer screen, requests access to his phone contacts and photo gallery, and does not provide a KFS before asking him to accept. He pauses.
Rahul compares the total repayment amounts — not just the EMI — and finds that the bank’s option, while slower to process, costs him less overall on a 12-month tenure. The NBFC option is legitimate and faster but costs more. The loan app option raises red flags: no lender name, no KFS, and excessive permissions. He waits one extra day and proceeds with the NBFC after reading its KFS and confirming its RBI registration status on RBI Sachet. The key insight: the fastest approval was the riskiest option, and the total cost — not the EMI alone — was what actually determined the right choice.
What You Typically Need Before Applying — By Route
Eligibility conditions vary by lender. The following list reflects typical requirements, not guaranteed minimums. Always check the specific lender’s current terms before applying. Credit score thresholds, income minimums, and document requirements change — verify at the lender’s website or from TransUnion CIBIL (transunioncibil.com) for bureau-related questions.
Bank Personal Loan
- Valid KYC: Aadhaar and PAN typically
- Salary slips (usually 3 months) and Form 16 or ITR
- Bank statements (typically 3 to 6 months)
- Acceptable credit bureau score — the threshold varies by bank
- Existing EMI obligations reviewed against your income
NBFC Personal Loan
- Valid KYC documents
- Income proof — some NBFCs accept bank statements alone for salaried borrowers
- Credit bureau check — the acceptable score range may be broader than a bank’s
- Existing EMI burden assessed against stated income
Loan App (Digital)
- PAN and Aadhaar for basic KYC
- Bank statement or salary slip in many cases
- Credit bureau check usually still happens — a “no CIBIL check” claim from an app is a warning sign
- App-level permissions: consent to access device data should be limited to what is necessary — contacts and gallery access are not required for a legitimate digital loan
- KFS must be provided before acceptance — if the app skips this, it is a compliance gap
Why APR Matters More Than the Advertised Rate
Many borrowers compare only the monthly interest rate shown on an app or lender website. This is not the full cost. Under RBI’s Digital Lending Directions, lenders are required to disclose APR — the Annual Percentage Rate — which gives a fuller picture of the cost of borrowing by including key charges over the loan tenure. Use the APR cost comparison guide to understand how to read this figure correctly.
Illustrative Example — Why Total Repayment Is What Counts
The figures below are illustrative only and are used to explain the concept. Do not treat them as current lender offers — rates, fees, and charges vary by lender and change over time.
Total Repayment = Principal + Total Interest + Processing Fee + Other Disclosed Charges
Where: Principal = loan amount borrowed | Total Interest = sum of all interest paid across all EMIs | Processing Fee = upfront charge deducted from disbursal or added to repayment
| Cost Item | Bank Example (Illustrative) | Loan App Example (Illustrative) |
|---|---|---|
| Loan amount | ₹1,50,000 | ₹1,50,000 |
| Tenure | 12 months | 3 months |
| Advertised monthly interest | 1.2% per month reducing | 2% per month reducing |
| Processing fee (illustrative) | 1% of loan amount | 3–5% of loan amount |
| APR (including fees) | Higher than stated monthly rate — verify from lender KFS | Significantly higher — short tenure amplifies effective cost |
| Total repayment (illustrative) | Lower over the full tenure | Higher — short tenure and fees can raise real cost sharply |
The point is not that all loan apps are expensive — it is that you cannot compare two loan offers fairly without comparing their APRs and total repayment amounts, not just the EMI. A 3-month loan from an app may feel affordable per month but cost significantly more in effective annual terms than a 12-month bank loan once the processing fee and short tenure are factored in.
What to Do If Something Goes Wrong
Step 1 — Contact the Lender or App’s Grievance Channel First
Every regulated lender — bank or NBFC — must have a grievance redressal officer. If you are using a loan app operated by an LSP, the regulated lender behind the app is still responsible for grievance resolution. Contact the lender’s grievance officer with your loan ID, KFS copy, payment proof, and a written record of the issue. Save all communication.
Step 2 — Escalate If Unresolved
If the lender does not resolve your complaint within a reasonable period, you can escalate to the RBI Integrated Ombudsman Scheme. The scheme covers banks and registered NBFCs. Contact details and the online complaint portal are available at rbi.org.in.
Step 3 — Cybercrime Portal for Fraud, Data Misuse, or Harassment
If a loan app has misused your personal data, impersonated a regulated entity, threatened or harassed you, or collected money without a legitimate loan agreement, report it at the National Cyber Crime Reporting Portal — cybercrime.gov.in. This route applies whether or not a real loan was disbursed.
| Problem Type | First Step | Escalation Route |
|---|---|---|
| Overcharge or hidden fee | Contact lender grievance officer with KFS and payment proof | RBI Ombudsman via rbi.org.in if unresolved |
| Incorrect deduction or unauthorized debit | Contact lender, then your bank to dispute the debit | RBI Ombudsman — save all transaction proof |
| Harassment by recovery agent or app | Contact lender grievance officer in writing | RBI Ombudsman; cybercrime.gov.in if threats or data misuse involved |
| Data misuse — contacts accessed or shared | File report at cybercrime.gov.in immediately | Local cybercrime cell if no online resolution |
| Fake loan app — money taken but no loan | Report at cybercrime.gov.in immediately | Local police cybercrime complaint with payment proof |
Safety Checklist: Before You Apply Through Any Loan App
- Identify the actual lender — the app must display the name of the RBI-regulated bank or NBFC that is lending the money.
- Confirm the lender’s registration — check the entity at RBI Sachet (sachet.rbi.org.in) or the RBI’s list of regulated entities at rbi.org.in. Use the loan app approval check guide for a step-by-step process.
- Read the KFS before accepting — the Key Fact Statement must be provided to you before you confirm the loan. If it is missing, do not proceed.
- Compare APR and total repayment — not just the EMI. The APR must be shown in the KFS.
- Review permissions — a legitimate loan app does not need access to your contacts, gallery, or location. Deny permissions that seem unrelated to a loan transaction.
- Save all proof — screenshot the KFS, loan offer, repayment schedule, and any communication with the lender or app before and after accepting.
- Check the grievance contact — a legitimate lender or LSP must display a grievance redressal officer name and contact details. If this is absent, that is a red flag.
For a full pre-application walkthrough, see the instant loan safety checklist.
How to Decide What’s Right for You
your CIBIL score is strong, your income is stable, and you have time to wait a few days — a bank personal loan often gives the lowest total cost and clearest complaint process.
a bank has declined your application but you have a steady income and a verified RBI-registered NBFC has offered you a loan with a clear KFS and reasonable APR — the NBFC route can be a legitimate alternative.
you are considering a loan app — only proceed after confirming the regulated lender name, checking registration status, reading the KFS, comparing APR, and reviewing the data permissions the app requests.
the loan is needed for non-essential spending and you are unsure whether you can repay within the offered tenure without stress — pause and assess whether borrowing right now makes sense regardless of which route you choose.
you cannot find a lender name, KFS, APR disclosure, or grievance contact in the app you are considering — do not apply through that app. These disclosures are not optional under RBI’s Digital Lending Directions; their absence is a compliance gap or a sign of an unregulated or fraudulent operation.
you have compared the total repayment amount — not just the EMI or the advertised rate — then you do not yet have the full cost picture. Calculate total cost before accepting any offer.
Common Mistakes to Avoid
Assuming the App Is the Lender
Many borrowers believe that the company whose name appears on the app is also the company lending the money. In many cases it is not — the app may be an LSP’s platform, and the actual lender is a bank or NBFC operating behind it. If you do not know who the lender is, you do not know who holds your data, who to repay, or where to complain.
Always ask: which RBI-regulated entity is disbursing this loan?
Ignoring the KFS and Accepting a Loan Immediately
The Key Fact Statement exists specifically to protect you before you commit. Skipping it — or accepting a loan before reading it — means you may not know the APR, total repayment amount, all fees, or the grievance contact until it is too late to withdraw without cost. Under RBI’s Digital Lending Directions, the KFS must be provided before acceptance. If an app skips this step, that is a problem with the lender or LSP, not a technicality.
Read every line of the KFS. Compare it to what the app showed you earlier in the process.
Comparing EMI Without Comparing APR
An app showing a ₹5,000 monthly EMI looks affordable. But if the loan tenure is 3 months and the processing fee is 4% of the loan amount, the effective APR could be substantially higher than the monthly rate suggests. Two loans with the same EMI can have very different total repayment amounts and APRs depending on tenure, fees, and other charges.
Compare total repayment and APR — not EMI alone.
Granting Contacts, Gallery, or Location Permission Casually
Some loan apps request access to your phone contacts, photo gallery, call logs, or location as part of onboarding. Legitimate lenders do not need this access to assess creditworthiness or disburse a loan. Granting these permissions to an unverified app creates serious data misuse risk. Review every permission the app requests before installing or registering. Deny any that are unrelated to your loan transaction.
Borrowing From an App With No Lender Name or Grievance Contact
If an app does not clearly display the name of the RBI-regulated entity lending the money, and does not provide a named grievance officer with contact details, you have no recourse path if something goes wrong. This is not a minor gap — it is a regulatory requirement under RBI’s Digital Lending Directions. Proceeding with such an app exposes you to hidden charges, data misuse, and recovery harassment with no legitimate complaint channel. For a detailed guide on identifying unsafe apps, see fake app warning signs before applying.
Trusting App Store Ratings or Download Counts as a Safety Signal
A high number of downloads or positive reviews on an app store does not confirm that the app is linked to a regulated lender. Fake or unregistered lending apps have appeared on official app stores before being delisted. The only reliable safety check is verifying the regulated entity independently through RBI Sachet or the RBI’s official list of regulated entities.
When This May Not Be the Right Choice
Borrowing through any route — bank, NBFC, or loan app — may not be the right move in these situations:
Your repayment is already stretched. If your existing EMIs already use up a significant share of your monthly income, adding another loan obligation may push your budget beyond what you can sustain. No lender type changes this arithmetic.
The loan would be used to repay another high-cost loan. Using a new loan to service an existing one can create a debt cycle. If this is the situation, explore whether a consolidation or restructuring conversation with your current lender is possible first.
The app terms are unclear or changing. If the loan offer, KFS, or repayment terms in the app seem inconsistent, incomplete, or are presented under time pressure — step back. Legitimate lenders do not pressure borrowers to accept before reading terms.
You are being pressured to accept immediately. Urgency tactics — “offer valid for 10 minutes,” “accept now or lose this rate” — are not standard practice for regulated lenders. Pressure to accept without adequate time to read the KFS is a warning sign.
No KFS or lender identity is disclosed. If the app cannot tell you who the regulated lender is and cannot provide a KFS before acceptance, the offer does not meet the minimum standard required under RBI’s Digital Lending Directions.
If any of these apply to your situation, it may be worth exploring other options before committing.
Official Rules and Where to Verify
The key regulatory framework governing digital lending in India is RBI’s Digital Lending Directions, which set out requirements for regulated entities and their LSP partners — covering KFS disclosure, APR, borrower consent, data access, loan disbursal account rules, and grievance redressal. The rules applicable to digital lending and the list of regulated entities can both change. Always verify current status before applying.
- RBI (rbi.org.in) — Primary source for the Digital Lending Directions, regulated entity lists, and the RBI Integrated Ombudsman Scheme complaint portal. Verify whether a lender is an RBI-registered bank or NBFC here.
- RBI Sachet (sachet.rbi.org.in) — Useful for checking whether an entity is registered and for reporting unauthorised or suspicious lending operations.
- TransUnion CIBIL (transunioncibil.com) — For understanding how a loan from any route may be reported to credit bureaus and how it may affect your credit history and score.
- National Cyber Crime Portal (cybercrime.gov.in) — The correct route for reporting fake loan apps, data misuse, impersonation of regulated entities, and harassment connected to lending.
Rules, rates, charges, and eligibility conditions can change. Always verify current details from the official source, lender, or relevant regulator before making a financial decision.
Expert Tips
- Screenshot the offer before you accept. Before tapping “accept” on any digital loan, take screenshots of the offer screen, the KFS, the repayment schedule, and the lender name. These screenshots are your evidence if anything is disputed later.
- Compare total repayment — not just the EMI. Two offers with similar monthly EMIs can have very different total costs depending on tenure, processing fee, and other charges. The KFS must show the total amount you will repay — use that number to compare.
- Check the grievance officer details before applying. A regulated lender must provide the name and contact of their grievance redressal officer. If this detail is absent from the app or website, that is a compliance gap — not a minor one.
- Deny app permissions that are unrelated to the loan. A legitimate lender does not need access to your contacts, camera, or gallery to assess eligibility or disburse a loan. Deny these permissions; if the app refuses to proceed without them, that is a red flag.
- Use RBI Sachet before you apply. Even if an app looks professional, spend two minutes verifying the lender’s name on RBI Sachet (sachet.rbi.org.in) before submitting any personal or financial data.
- Never borrow under pressure. If an app or agent creates urgency — limited-time offer, immediate acceptance required — pause. Regulated lenders do not need to pressure you into accepting a loan without time to read the terms. That pressure is itself a warning.
- Keep proof of every repayment. Save every transaction confirmation, repayment receipt, and debit alert related to any loan. If a dispute arises about your repayment history, these records are essential.
Frequently Asked Questions
Is a loan app the same as an NBFC?
No. A loan app may be a digital platform operated by the bank or NBFC itself, or it may be a third-party LSP that is not a lender at all. The NBFC is the regulated entity; the app may just be the interface. Always look past the app to identify which RBI-registered bank or NBFC is the actual lender.
Are loan apps legal in India?
Loan apps that are operated by or on behalf of RBI-registered banks and NBFCs — and that comply with RBI’s Digital Lending Directions — are legal. Apps that operate without a regulated lender behind them, or that violate disclosure, data, or conduct rules, are not compliant with RBI requirements. Legality depends on the regulated entity behind the app, not the app itself.
Is it safer to take a loan from a bank than from an NBFC?
Both banks and NBFCs are regulated by RBI, and both can be legitimate sources of borrowing. The safety difference is more about the specific lender’s terms, disclosure practices, grievance process, and your ability to verify their regulation status — not simply bank vs NBFC. A verified, compliant NBFC can be a safer borrowing choice than an app with no disclosed lender at all.
Can a loan app disburse money without an RBI-regulated lender behind it?
No. Under RBI’s Digital Lending Directions, only RBI-registered banks and NBFCs can lend money in India. A loan app or LSP cannot legally disburse loans on its own. If an app is offering you a loan but cannot name the regulated entity lending the money, that is a serious red flag — possibly indicating an unregistered or fraudulent operation.
What should I check before applying through a loan app?
Identify the regulated lender name, verify their registration on RBI Sachet or rbi.org.in, read the KFS before accepting, compare APR and total repayment, check what device permissions the app requests, and note the grievance officer contact details. Do not proceed if any of these is absent.
Do loans from banks, NBFCs, and loan apps all affect my CIBIL score?
Yes. Any loan from a bank or NBFC that is disbursed under a formal loan agreement will typically be reported to one or more credit bureaus — TransUnion CIBIL, Experian, Equifax, or CRIF High Mark — regardless of whether it came through a branch, an NBFC office, or a digital app. On-time repayments generally support your credit history; missed payments or defaults can damage it. Verify credit bureau reporting with TransUnion CIBIL (transunioncibil.com) for details.
Where can I complain about a fake or harassing loan app?
For fraud, data misuse, impersonation, or harassment connected to a loan app, report at the National Cyber Crime Reporting Portal — cybercrime.gov.in. If the complaint involves a regulated lender or their LSP, escalate to the RBI Integrated Ombudsman Scheme via rbi.org.in after first contacting the lender’s grievance officer. Save all evidence — screenshots, transaction proof, communication records — before filing.
What is the KFS and why must I read it before accepting a digital loan?
The Key Fact Statement (KFS) is a standardised summary document required under RBI’s Digital Lending Directions. It must be provided to you before you accept a digital loan and must include the APR, all fees and charges, the total repayment amount, the repayment schedule, and the grievance officer contact. Reading the KFS lets you know the real cost of the loan and confirms your complaint route before you commit.
Final Verdict
The bank vs NBFC vs loan app question is not really about which type of institution is universally better. It is about understanding who is actually lending the money, whether that entity is RBI-regulated, and what cost and complaint protections you have before you commit. Banks are familiar and regulated with defined complaint paths, but tend to be stricter on eligibility. NBFCs are also regulated and can be more flexible, but terms vary widely — always check the KFS, APR, and total repayment before accepting. Loan apps are where the most risk lives: many are legitimate platforms connected to regulated lenders, but some are not, and the app interface can obscure who is actually responsible for the loan.
Before applying through any route, the non-negotiable checks are the same: identify the regulated lender, read the KFS, compare APR, review data permissions, and save proof of everything. Speed of approval is not a measure of safety. Always verify the latest rules, charges, and terms from the relevant official source or provider before making a financial decision.
This article is for educational purposes only and should not be treated as personalised financial, credit, tax, or legal advice. Rules, rates, charges, eligibility criteria, and product terms can vary by provider and may change over time. Please verify current details from official sources, the relevant provider, or a qualified professional before making any financial decision.
Arjun writes clear borrower-safety guides on digital loan apps, RBI digital lending rules, KFS, APR, LSPs, loan app harassment, cybercrime complaints, CIBIL impact, and safer borrowing choices. He focuses on helping Indian borrowers understand risks, protect their data, compare lenders carefully, and use official complaint channels when needed.